Important now

Check our newest soultions in the scope of property tax, family foundations, R&D tax relief, B2B contracts and many more!  

Check our newest soultions in the scope of property tax, family foundations, R&D tax relief, B2B contracts and many more!  

Premiere of the Made in Poland Report 2024

Premiere of the Made in Poland Report 2024

Poland: A Prime Destination for Businesses Aiming to Contribute to Ukraine’s Recovery

Poland: A Prime Destination for Businesses Aiming to Contribute to Ukraine’s Recovery

ESG at ALTO – Ewa Solarz will head a new business line

ESG at ALTO – Ewa Solarz will head a new business line

Katarzyna Adamowicz joins the group of TAX managers at ALTO

Katarzyna Adamowicz, recently acting as a tax advisory department director at one of the largest accounting companies in Poland, returns to ALTO after years to take the position of Senior Manager in the TAX team.

Katarzyna has been advising clients in the area of ​​both direct and indirect taxes for over 10 years. She deals with ongoing tax consultancy, and also implements projects aimed at minimizing tax risk and achieving tax savings. What is more, Katarzyna managed many complex legal & tax projects and represented her clients before tax authorities or administrative courts. Her experience includes also consulting for international and domestic companies.

At ALTO, Katarzyna will continue advising corporate clients. As part of the TAX team, she will design and develop services in the area of ​​indirect taxes.

“I am very happy that we will be able to cooperate with Kasia again. Only a few know that she started her professional path at ALTO – at the very beginning of the company’s existence. Now, richer with experience and skills, we are joining forces again to strengthen the best client experience in our tax business line. We are convinced that our clients will feel very positively that Kasia, with her professionalism and efficiency, is a significant professional for ALTO team strengthening. “ – says Kamil Lewandowski, Managing Partner at ALTO.

Kasia is a graduate of the Faculty of Journalism and Political Science at the University of Warsaw and the Warsaw School of Economics. She is a licensed tax advisor since 2015, an author of numerous press publications and a co-author of books, incl. “Meritum taxes 2019”, “Accounting and tax instructions 2018”, “Accounting and tax instructions 2019” and “Accounting and tax instructions 2021”.

“I took my first steps in consulting at ALTO, and even though the company now has not a dozen, but almost 150 employees, I feel again that this is my place. Extremely warm and cordial welcome gives the impression of returning to your homeland. I hope that I will be able to use the experience gained in recent years in new, interesting projects, which will not be lacking due to the constantly growing demand for consulting services, both business and tax. Over the last few years I have watched how the team at ALTO is developing dynamically and how it gathers great experts on board. I am glad that I could join them. “ – says Katarzyna Adamowicz, Senior Manager, Tax Advisor at ALTO.

It’s not so easy to run away with taxation abroad

A taxpayer is considered to be a Polish tax resident because he has a management board in Poland, also when his current affairs are conducted here in an organized and continuous manner, despite having a registered office in another.

Determining tax residence should not be problematic by definition. If an economic entity is registered in Poland and conducts its economic activity here, then – in accordance with the general rule – it is subject to taxation on all its income in Poland. But is it only then? Not necessarily.

For years, legislators around the world have been waging an unequal race with the economic reality, trying to adjust the regulations (including tax regulations) to its level of complexity and the pace of changes. The digital revolution and the fact that an increasing part of services can be delivered remotely and the fact that physical presence is no longer crucial for effective business management and decision-making makes it not so obvious to determine the tax residence of a given entity.

The concept of tax liability is inextricably linked with tax residence. Currently, this issue is governed by two provisions – Art. 3 sec. 1 of the CIT Act, specifying the so-called unlimited tax liability, and art. 3 sec. 2 of the CIT Act, which constitutes a limited obligation.

Pursuant to the first of the above-mentioned provisions, tax residents are entities that have their registered office or management board in Poland and, as a result, are obliged to pay corporate income tax in Poland on all their income, regardless of where it is earned (i.e. also on income earned abroad). Accordingly, tax non-residents are taxed in Poland only on the income they receive in the territory of the country.


Bilateral agreements are helpful

Insightful readers will immediately realize that a given taxpayer may have an unlimited tax liability in Poland and a limited tax liability abroad (e.g. in the Czech Republic). It may then come to a situation where the right to tax Czech income will be claimed by both the country in which this income is earned (in our example – the Czech Republic) and Poland, due to the unlimited nature of the tax obligation. To avoid such situations, bilateral international agreements on the avoidance of double taxation are signed.

This example shows how important it is to determine whether a given entity has limited or unlimited tax liability in Poland. In practice, this may turn out to be troublesome, because the construction of the definition of a tax obligation indicates that entities not having their registered office in Poland, but having a place of management here, can still be considered Polish tax residents. While determining the place of the seat is objective and usually does not cause problems, determining the place of management is much more subjective and often requires the use of the so-called professional judgment.

This is due to the fact that, unlike the place of seat, it is difficult to clearly determine the place of management on the basis of the formal status of the entity, i.e. information resulting from founding acts or official registers, such as, for example, the National Court Register.

The answer to these difficulties is to be a provision clarifying the definition of the Polish place of management.


Changes from January 1

A lot of talk about establishing a tax residence began with the appearance of the first projects of the Polish Deal. The proposed changes turned out to be unfavorable for many Polish entrepreneurs and for the self-employed, who began to threaten with business emigration to, for example, the Czech Republic or Slovakia. It seems that these voices were also listened to by the legislator who, as part of the amendments to the amendment, decided to clarify the definition of the place of management in Poland and to take into account this type of practice.

Pursuant to the provisions of the provision (Article 3 (1a) of the CIT Act), which entered into force on January 1, 2022, the taxpayer will be considered a Polish tax resident due to having a management board in the territory of Poland, also in a situation where his current affairs are conducted in an organized and continuous manner on the territory of Poland, despite being based in another country. At the same time, the basis for running the company’s affairs can be basically everything (the provision uses an open catalog), i.e. provisions of the articles of association, court decisions, powers of attorney granted or the existence of connections within the meaning of the provisions on transfer pricing. The main purpose of these changes, according to the justification to this provision, is to prevent Polish residents from establishing companies abroad that are effectively managed from Poland.


Effects also on holding companies

It is worth noting that the commented change may also affect businesses that have been operating abroad for years, but have Polish tax residents as board members. Many international enterprises (including Polish companies that expanded their activities abroad) decided to establish foreign holding companies, e.g. in order to organize the capital structure or to ensure access to foreign investors and financing.

Due to their experience and position in the organization, foreign holding companies are often managed by Poles. In the event that these persons (on their own or acting with other Polish directors) can make decisions that are binding on a foreign company (i.e. they represent it), the amendment may result in an unintentional change of the tax residence of such a company to a Polish one, which in turn may result in – at least temporarily – double taxation of its income.

To sum up, the commented change should encourage capital groups with an international reach to verify the current holding structure and the adopted corporate governance. And those who intend to flee with business abroad should prepare for this emigration a little better than just by registering a business in another country.

Dziennik Gazeta Prawna: There is no PCC from goodwill

An important judgment of the Supreme Administrative Court was passed regarding the positive value of the company and its taxation on PCC (tax on civil transactions).

The Supreme Administrative Court issued a judgment (Resolution of the Supreme Administrative Court of February 21, 2022, reference number III FPS 2/21) regarding whether the positive goodwill of the so-called goodwill is property law and should it be subject to PCC.

The judges decided that goodwill is not a property right, even though it has a financial dimension. Therefore, it should not be taxed with the tax on civil law transactions.

The decision of the Supreme Administrative Court for Dziennik Gazeta Prawna is commented on by our expert – Łukasz Kalisz, Senior Consultant, tax advisor, advocate at ALTO:

,,The Supreme Administrative Court rightly stated that positive goodwill does not constitute a property right. Although goodwill has a certain property dimension, its value can be determined in some way, it is also subject to depreciation for income tax purposes, but it cannot be a separate, independent subject of trade. The resolution of the Supreme Administrative Court was adopted in a specific administrative court case, but the conclusions resulting from its thesis and justification will have a wide impact on the interpretation of the provisions of the PCC Act. This decision is a very strong argument in favor of the correction of the declaration and recovery of tax overpayment. It can also be a premise for use in pending disputes with tax authorities.”

*** The full text of the article is available on podatki.gazetaprawna.pl

How can insurance innovations reduce taxes?

We are witnessing the dynamic development of modern technologies and business solutions based on them. The trend was additionally accelerated by the pandemic, which forced entrepreneurs to transfer a large part of their activity to virtual reality.

More and more innovative solutions are used in the insurance industry, which is noticeable in the interactions of insurers both with clients and agents. The creation and development of tools increasing the competitiveness of insurers is associated with incurring expenses. Thanks to the R&D tax relief, such costs may be refinanced and may result in real savings.


What is R&D relief?

The R&D tax relief is a solution that allows for the deduction of costs related to R&D activity from the CIT tax base. In order to recognize the activity as research and development, it is necessary that the entrepreneur, within his own resources, works on innovative solutions on the scale of his own activity (even if they are already available on the market).

In practice, the mechanism of applying the tax relief is not complicated. A specific expense constituting a tax cost (reducing taxable income) can be deducted again from the tax base, which in turn reduces the tax payable. We can apply the relief on an annual basis, also in relation to previous tax years (from 2016).

At first glance, the relief seems to be a solution dedicated to technology, IT or industrial companies. However, also in the insurance industry, we can find many examples of R&D activity, in particular regarding internal software or applications made available to clients – we presented them later on in the text.


What costs do we deduct?

The regulations provide for a wide range of costs that may be deducted as part of the R&D relief. From the perspective of applying the tax relief in the insurance industry, the key factor is the possibility to deduct the costs of remuneration of both employees and persons employed under a mandate contract or a specific specific task contract. The deduction also covers ZUS contributions paid by the entrepreneur. Unfortunately, it is not possible to settle expenses for the remuneration of associates who provide services on the basis of B2B as part of the relief. It is possible to deduct, for example, from depreciation of fixed assets (e.g. computers) or intangible assets (e.g. software) used as part of R&D.


How much are we cutting down?

The R&D tax relief has been in force since 2016 and has changed significantly during this period, in particular with regard to the value of deducted costs. Year by year, the legislator encouraged more and more to undertake R&D activities and to use the tax relief. Initially, only 30% of the value of eligible costs could be deducted. In 2017, it was 50%, while from 2018, 100% of eligible costs are deducted. The last change was introduced as part of the Polish Order, from 2022, deduction as part of the relief is 200% of payroll costs and 100% of other costs. Thus, in Poland we currently have one of the most attractive, if not the most attractive tax relief of this type, and a similar instrument is used in many countries.

What financial benefits can the implementation of the tax bring? For example, if in 2021 a taxpayer incurred PLN 1,000,000 of remuneration costs as part of R&D activities, the real savings on CIT will be PLN 190,000. From 2022, it will be PLN 380,000 tax benefit. Such a level of support for large entrepreneurs is often not available even in the form of a grant for an innovative R&D project on the market scale, while the use of subsidies, i.e. selectively granted public aid for R&D activities, is associated with very significant restrictions and administrative effort .


How to use the relief?

R&D relief is not a state aid as it is not selective – it is granted to everyone on the same terms. To use it, it is enough to take the following steps:

  • identifying projects / areas of activity that meet the definition of R&D activity,
  • assigning eligible costs to them.

The relief is settled at the end of each year in the CIT-8 declaration and there are no contraindications to settle several previous years at the same time in the form of correction of tax declarations. In terms of future periods, however, it is worth considering a possible improvement of the processes.

More and more entrepreneurs use the tax relief, and the practice of tax authorities is already well known. Appropriate documentation prepared for the purpose of including the tax relief in the tax declaration will be completely sufficient if the tax office has questions.


The insurance industry is innovative

The assessment of the possibility of using R&D relief in the insurance industry is simple. It is enough to visit the websites of several exemplary insurance companies to find out that the insurance industry has a great potential to use R&D relief, and the solutions implemented by insurers are undoubtedly innovative. Some of them are already effectively using the tax credit, but this is a small percentage of eligible companies.

What can the insurer’s R&D activities involve? These can be any solutions used in the process of insurance distribution and service, or for the internal needs of the organization. As examples, we can mention, among others:

  • software enabling remote purchase of policies;
  • risk assessment systems;
  • solutions improving customer service (e.g. the so-called voicebot);
  • mobile application for customer service;
  • automation of claims handling processes;
  • data protection solutions.

R&D activity can also potentially include works related to the development of the system for selling and servicing policies used by the insurer and its agents.

In our opinion, insurance companies that develop independently indicated solutions with the use of internal resources can consider applying the relief in relation to their tax settlements.


Is it worth taking advantage of the R&D tax relief?

The tax changes introduced in recent years increase the tax burden on entrepreneurs and impose new obligations on them. R&D relief, on the other hand, is a positive accent that allows taxpayers to obtain significant financial savings. It can be an interesting solution to reduce taxation “on the occasion” of the development of various types of innovations as part of the conducted activity.

At the same time, it must be remembered that the use of the tax relief is relatively simple and does not generate any significant tax risk. Therefore, it is worth analyzing within the organization the possibility of implementing R&D relief right now, when the tax settlement for 2016 has not expired and can be covered by it.

Puls Biznesu: Inetum jumped several years ahead thanks to the acquisition

The beginning of the year is one of the most active in terms of the number of transactions behind us, and the wave of consolidation may continue to grow.

Gigant Inetum specializing in digital transformation took over the Polish company JCommerce and thus rapidly strengthened its presence in our country. Our expert Rafał Kozłowski (Counsel & Attorney-at-law, ALTO) comments on the consolidation movements on our IT market and the M&A forecasts for Puls Biznesu:

The wave of consolidation is yet to come

“The domestic market of IT companies supporting digital transformation is in the initial phase of consolidation, but it looks extremely promising. In addition to global factors, such as technological progress and the acceleration of digital transformation forced by the COVID-19 pandemic, there are also conditions specific to the market on the Vistula: staff shortages and the growing number of start-ups. The first wave of succession of enterprises in Poland, the reins of which is taken by the younger generation – focused on changes and simplification of management processes, may also turn out to be of key importance. The market is mainly consolidating around the largest IT and consulting players. Due to more difficult access to financing, family businesses are usually taken over by larger and more recognizable entities. In the domestic market, competition is visible primarily in the fight for an employee, which mainly concerns programmers and IT managers. ”

The full text of the article is available at: www.pb.pl/inetum-przeskoczylo-kilka-lat-dzieki-akwizycji 

Tax strategy in 2022

Experiences from 2021

In 2021, companies reported their tax strategy for the first time. For most of our clients, the challenge was to formulate a report that, on the one hand, would provide information about the organization of the tax function, and at the same time would not expose the company to the risk of disclosing sensitive information. These projects also showed that postponing work until the last quarter of the year is not recommended.


Reporting in 2022

Information on the implemented strategy must be updated and published every year. Companies that published the strategy in 2021 and still meet the reporting conditions will have to update the published information in 2022.


Additionally, for the first time in 2022, the strategy will be published by:

  • companies that only in 2021 exceeded the threshold of EUR 50 million in revenue;
  • limited partnerships which in 2021 became CIT taxpayers and could exceed the above-mentioned threshold (potentially also general partnerships).


How can we help?

Our experience shows that the preparation of comprehensive and safe information about the implemented strategy is a process that consists of several key stages.

ALTO experts are ready to support you at every stage of preparing information on the tax strategy – from the mapping of tax processes, through the formulation of the strategy, to the publication of information on the tax strategy.

Dziennik Gazeta Prawna: You can recover overstated VAT shown on the receipt

Is it possible to recover the overstated VAT shown on the receipt? The correction of the amount of this tax in the case of sales documented with receipts is still the subject of disputes with the tax authorities.

According to the ruling of the Supreme Administrative Court, the overpayment of VAT should also be received by the entrepreneur who passed the cost on to consumers and suffered no financial loss.

Our expert, Łukasz Kalisz, comments for Dziennik Gazeta Prawna on the proceedings conducted by ALTO experts regarding overpayments in VAT and describes why, in his opinion, retailers cannot be discriminated against when refunding VAT overpayments:

“The correction of VAT rates for sales documented with receipts is still the subject of disputes with tax authorities. There are views that such a correction is impossible, because it is not allowed by the correction rules set out in the regulation of 2013 on cash registers and that it is not possible to obtain confirmation of the correction by the buyer (see the judgment of the Supreme Administrative Court of July 1, 2020. , reference number I FSK 1725/17) or that the taxpayer would obtain an undue benefit at the consumer’s expense with such a correction. However, the latest judgments of the Supreme Administrative Court show that such assumptions are incorrect and that taxpayers who document the sale with receipts have the right to correct their settlements and to claim a refund of VAT overpayment when they unjustifiably overestimate the tax rate.

The key is that entrepreneurs selling to consumers cannot be discriminated against against taxpayers who can correct the issued invoices. It is also irrelevant that the value of the VAT will not be reimbursed to consumers. The premise for the recovery of the overpayment is not the burden of VAT. It is only important that the tax has been paid to the tax office in the amount higher than the amount due. As a side note, it should be noted that the burden of VAT is always passed on to the buyer, so if the position of the authorities was considered correct, an overpayment in VAT would never arise. “

The full text of the article is available at: https://podatki.gazetaprawna.pl

Estonian CIT in practice

Lump sum on the income of capital companies, popularly known as the Estonian CIT, was introduced to the Polish legal system at the beginning of 2021 as an alternative form of taxation to the general rules. The first version of this model of taxation, however, was quite far from its Estonian prototype, which was to be a determinant of a pro-investment, taxpayer-friendly and maximally informal form of taxation.

Therefore, at the beginning of 2022, an amendment to the regulations came into force to convince Polish entrepreneurs to choose to tax with Estonian CIT. As part of the introduced changes, not only the name of the model has been modified, i.e. now we are talking about a lump sum on company income, but also the group of taxpayers entitled to apply the lump sum has expanded, or the requirements for the application of this preferential taxation method have been “loosened”. As a result of these changes, and in the face of increasing tax burdens in connection with the so-called In the Polish Government, the Estonian CIT is becoming an alternative taxation for Polish taxpayers worth considering. In such a situation, it is worth looking at several practical aspects of the Estonian CIT, which, although addressed in theory in the regulations, may still raise significant doubts in practice.


Starting the copmany and transformation

The CIT Act provides for two tax rates for Estonian CIT – 10%. applicable in the case of a small taxpayer and a taxpayer starting business, and 20 percent. In other cases. What about taxpayers who were established as a result of transforming, for example, a sole proprietorship into a limited liability company? or also partnerships, e.g. general partnership? In such a situation, it can be concluded that we are dealing with the commencement of business, since in practice the establishment of a company is a continuation of the economic activities carried out? The analysis of the provisions of the CIT Act relating to taxpayers starting business activity (i.e. taxpayers within the meaning of the CIT Act) and the “Guide to the lump sum on company income” published on 23 December 2021 (hereinafter: the Guide) shows that in such a situation we have to dealing with starting a business. In addition, the Guide emphasizes that the transformation of a sole proprietorship into a business start-up is not a restructuring activity listed in Art. 28k paragraph. 1 points 5-6, which would make it impossible to apply the lump sum.

As a result, entrepreneurs conducting sole proprietorship or general partnerships, after the transformation, are entitled to apply the 10% rate of Estonian CIT in the first year after the transformation.

In this case, it is worth noting that the possibility of applying the lower of the Estonian CIT rates for start-ups was introduced only under the provisions in force from January 1, 2022.

Therefore, the legislator met the expectations of entrepreneurs who can benefit from the preferential rate not only if their revenues do not exceed PLN 2 million, but also when they have just started operating in the form of a company.


Not only dividends

The key attribute of Estonian CIT is no need to tax the profit earned, and as a result, no need to pay monthly or quarterly CIT advances until its payment. The CIT Act indicates the events that will result in the obligation of the flat-rate payer to settle the tax, i.e .:

  1. allocating the profit earned in the period of taxation with a lump sum to be paid to shareholders (payment of dividends, but also advance payments for dividends) or to cover losses incurred before the tax period of Estonian CIT (adopting a resolution to allocate the generated profit to cover losses from previous years),
  2. the rise of income from the so-called hidden profits
  3. incurring expenses not related to the conducted activity,
  4. excess of the market value of the assets being acquired over the tax value of these assets (income from changes in the value of assets) – in the case of transformation of entities,
  5. obtaining income from the so-called undisclosed business operations.


While payments to shareholders or a surplus resulting from transformations seem to be a fairly obvious method of payment of profit, which causes the necessity to pay the tax, the definition of the so-called hidden profits. Also in this case, the legislator hurries to explain by pointing to an exemplary catalog of activities that may generate taxation as hidden profits.

And so, among these types of events, one should mention,is granting loans to partners or entities related to them, as well as benefits for private foundations or trusts and donations, including gifts and offerings of all kinds, or underestimating the market value of transactions with a related entity. It should be noted here that the list of transactions contained in the CIT Act is not exhaustive and in practice all kinds of benefits for partners, but also for their families as related entities, can be treated as income from the so-called hidden profits.

In addition, a category that raises some doubts, causing the necessity to pay the tax is also incurring expenses not related to the conducted activity. The CIT Act in no way specifies what falls into this category, although a vague explanation can be found in the Guide. According to the Guide, in the case of analyzing whether we are dealing with an expense not related to the conducted activity, it is possible to use not only the qualification of expenses as non-tax costs in accordance with Art. 15 sec. 1 of the CIT Act, but also the entity’s current practice (helpful if it was a CIT taxpayer) and court and administrative judgments. And so, as an example of expenses not related to the conducted activity, one should indicate, inter alia, interest and contractual penalties excluded from the category of tax costs pursuant to Art. 16 of the CIT Act. By the way, it is worth pointing to the case-law favorable to taxpayers in the field of contractual penalties arising in the event that breaking the contract was more economically beneficial for the taxpayer than maintaining it. As a result, despite the fact that taxpayers taxed with Estonian CIT do not recognize tax revenues and costs based on the regulations contained in Art. 15 and 16 of the CIT Act, knowledge of these regulations, but also of jurisprudence, may be crucial in the case of, inter alia, identification of expenses not related to the business activity leading to the obligation to pay the tax.


Taxation of partners

In the case of CIT taxpayers, there is double taxation of profits generated by these companies. This means that the payment of profit is taxed both at the level of the company that is a taxpayer of Estonian CIT (10% or 20% of the value of the payment, e.g. dividend) and at the level of a partner who is a natural person (19% PIT rate for revenues from capital gains). ).

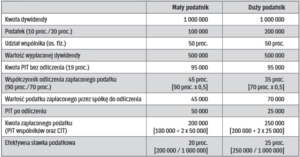
At the same time, the CIT Act provides for the mechanism of deduction by the partners of the tax paid by the company from the due PIT tax. The amount of the deduction in this case depends on whether the taxpayer of Estonian CIT will have the status of a small taxpayer or not. In the case of a withdrawal from a non-small taxpayer company, the deduction ratio will be 70%. the amount of tax due to the company per shareholder, and in the case of a small taxpayer it is 90 percent. Consequently, the total taxation of profits in a small taxpayer is 20%, and in other cases 25%.

Illustrating it on a numerical example, assuming that an Estonian CIT taxpayer has two partners, each of whom has 50 percent. shares: >> see table below.
Author’s view

Katarzyna Zadroga, tax advisor, Senior Consultant at ALTO

The amendment to the regulation on lump sums from companies, which entered into force on January 1, 2022, will certainly be an incentive for Polish taxpayers looking for an alternative method of taxation, bearing in mind the unfavorable consequences of the Polish Deal, in particular for entrepreneurs operating on a smaller scale. lowering the requirements for the application of Estonian CIT or reducing tax rates may seem particularly attractive for sole proprietorships or partnerships which, due to the planned business development, will decide to operate in the form of a CIT taxpayer company. Therefore, the benefit achieved by such companies in the event of a decision to use the Estonian CIT taxation option would be not only to systematize the issue of potential business development, but also to reduce the tax burden imposed on sole proprietorships by the regulations of the Polish Deal.

Regardless of the above, it is worth noting that the Polish lump sum on company income is still far from its Estonian prototype, especially when it comes to the simplicity of operation and the number of reporting obligations. It still does not explicitly follow from the provisions, inter alia, How should the income from the transformation of companies be documented (in such a situation, should a zero declaration be submitted on the CIT / KW form?). As a result, it seems that possible regulatory deficiencies will be explained by the practice of tax authorities, as irrespective of the numerous reporting obligations, one may hope that soon we will notice a significant increase in the number of taxpayers choosing this form of taxation, due to the fact that the alternative for Estonian CIT it is in practice to pay higher taxes than in 2021.

The president signed the holding law

We briefly recall the most important changes introduced to the Polish legal system by the said amendment to the Commercial Companies Code.

On April 4, 2022, the President signed the government bill amending the Commercial Companies Code (KSH) and certain other acts (print 1515). Earlier, the Sejm rejected the Senate’s resolution rejecting the bill. Due to this, the new regulations refer to a large extent (but not only!) To the legal relations between parent companies and their subsidiaries, hence they are often referred to as the so-called “Holding law”.

Below, we briefly recall the most important changes introduced to the Polish legal system by the amendment to the Commercial Companies Code.


Holding law

For the first time in the Polish legal system, regulations concerning the law of a group of companies (holding law) appear, referring directly to actual holdings.

A statutory definition of a “group of companies” is introduced – as a parent company and a company or subsidiaries that are capital companies, guided by a common strategy in order to achieve a common interest (interest of a group of companies), justifying the parent company exercising uniform management over a subsidiary or subsidiaries . It is worth emphasizing that, according to the Act, a “group of companies” is a qualified relationship of dominance and dependence between companies that follow a common economic strategy. It is therefore necessary to distinguish a “group of companies” from the “ordinary” relationship of dominance and dependence between companies, as referred to in Art. 4 § 1 point 4 of the Commercial Companies Code. It is essential for group law that the parent company and subsidiary of a group of companies must also take into account the “interest of the group of companies” in addition to the own interests of each company.

Participation in the group of companies is voluntary. It requires adopting a resolution of the shareholders’ meeting (general meeting) of the subsidiary with an indication of the parent company and disclosure of participation in the group by entering a note in the register. The parent company may issue binding instructions to the subsidiary participating in the group regarding the conduct of the company’s affairs.

More on the institution of binding orders and responsibility for their execution: < under this link >.


Changes in the law of compulsory buyout and repurchase of shares (stocks) of minority shareholders (squuze-out and sell-out)

The legislator has increased the availability of the use of the institution of compulsory buyout of shares (stocks) – squuze out, moving this institution also to a limited liability company. So far, the squuze out has been available only under the provisions of S.A. In addition (both in the case of S.A. and sp.z o.o.), the statutory thresholds for its application have been liberalized – in principle, a compulsory buyout may apply to shares or stocks representing no more than 10% of the share capital by the parent company that has at least 90% of the share capital ( so far, squuze out was only possible with regard to minority shareholders representing no more than 5% of the share capital by shareholders representing at least 95% of the share capital).

Identical statutory solutions – i.e. introducing the institution also in sp.z o.o., liberalization of the application conditions (the same as in the case of squueze out) were applied to the sell-out institution – compulsory repurchase of shares / stocks belonging to minority shareholders of a subsidiary.

It is worth noting that the above (new regulations) regarding squuze-out or sell-out apply to companies participating in the group of companies. Regardless of this, the current squuze out (sell-out) mechanism on general principles for private S.A. (Art. 418 of the Commercial Companies Code), including the conditions for its application, remain unchanged.


Broader powers of supervisory boards, more effective supervision

The new regulations provide for more specific rights and obligations of the supervisory board in order to increase the effectiveness of supervision in capital companies. The amendment to the Commercial Companies Code also places emphasis on the effectiveness of maintaining the information balance between the management board and members of the supervisory board, and on the control mechanisms of supervisory boards.

The provisions introduce, among others: the right of the supervisory board to request preparation / submission of information, documents, reports, explanations, the obligation of the management board to provide certain specific information to the supervisory board on its own initiative, new reporting obligations of the supervisory board, regulations on supervisory board committees, a new instrument as an advisor to the supervisory board (an external entity with expertise and qualifications to audit specific issues).


Changing the liability rules for members of the management board and members of supervisory boards

The rules of liability of members of corporate bodies will be based on the category of “business judgment” – the business judgment rule. The amendment to the Commercial Companies Code explicitly stipulates the obligation of loyalty of members of the management board and supervisory board of capital companies. A member of the body is obliged to perform his duties with due diligence resulting from the professional nature of his activity and to remain loyal to the company. In practice, based on the principle of business assessment of the situation, a member of an authority does not breach the obligation to exercise due diligence if he or she has consulted, in the performance of his duties, analyzes that should be taken into account in the given circumstances when making his assessment.


A new way of shaping the term of office and mandates of members of company bodies

The amendment resolves the doubts of the doctrine and jurisprudence regarding the determination of the moment of expiry of the mandate in connection with the end of the term of office. As a general rule, the term of office is calculated in full financial years (unless otherwise stated in the articles of association).


An extended catalog of people excluded from performing functions in company bodies

The catalog of persons excluded from being a member of the body, liquidator, and proxy has been expanded. The extension of the catalog of excluded persons is related to the extension of the catalog of crimes for which a person to be a member of the body, liquidator or commercial proxy cannot be convicted by a final judgment. In the criminal part of the Commercial Companies Code, additional types of crimes appeared.

You can read more about the liability of members of bodies in capital companies based on the new regulations in the article by Urszula Brzezińska-Grzęda and Tomasz Fiałek (ALTO)<under this link >

Amendments to the new draft act on whistleblowers

On April 12, 2022, on the website of the Government Legislation Center, a new draft act on the protection of persons reporting violations of the law, commonly known as the Whistleblower Act, was published.

The act is to implement Directive (EU) 2019/1937 of the European Parliament and of the Council of 23 October 2019 on the protection of persons who report breaches of EU law. The above directive provided for the implementation of the whistleblower protection provisions by 17 December 2021, but this deadline was not met. The original bill, prepared in October 2021, after consultations and as a result of comments submitted during the opinion-giving process, was subject to significant changes, on the basis of which a new draft was prepared.

It is not known when the bill will be debated by the Seym, therefore it is difficult to predict the final date of signing and entering into force of the act, but due to the exceeded deadlines, a significant acceleration of the legislative process cannot be ruled out.

The new draft provides for many significant changes in relation to the original assumptions of the amendment – from a change in the scope of companies covered by the obligation to introduce a breach notification procedure, through entities dealing with external reports, changes in penalties for prohibited acts, to a change in the vacatio legis period.

The most significant changes in the draft of April 2022 in relation to the first draft include the extension of the scope of entrepreneurs who will be covered by the Act. While the size of the company remains the same as in the original project, the method of calculating this size has changed. This is because it results from two changes – firstly, the definition of the entity obliged to introduce the procedure has been changed. In the previous project, he was defined as an employer within the meaning of the Labor Code. However, it was postulated that this definition was too narrow and that the procedure should also include people cooperating with the enterprise on the basis of civil law contracts. Moreover, in order to standardize the scope of persons who will be entitled to exercise the rights of whistleblowers, the definition of them as an employee within the meaning of the provisions of the Code of Civil Procedure was abandoned and the existing catalog was extended to include apprentices or the so-called uniformed services. The new version of the draft reduces the period of data storage in the register to 12 months. A significant change also consists in extending the scope of the prohibition of retaliation to the reporting person. There was also a ban on attempting such actions as well as the mere threats to do so. The new draft also introduces changes to the mandatory notification procedure, including the inclusion of a system of incentives to use it in the procedure.

Another significant change is the removal of the use of the term “central authority” in favor of a public authority. This change is probably due to an erroneous use of the term central authority, as its activities are to be performed by the Ombudsman, who is not a central authority within the meaning of the provisions, in accordance with the draft act. On the other hand, the penal provisions provided for in the draft act were relaxed. For example, obstructing or attempting to obstruct the reporting process is subject to a penalty of a fine or restriction of liberty (previously imprisonment for up to 3 years, which, however, remains appropriate for a situation of using violence, threats or deception). The last change – although one of the most important from the point of view of the companies covered by the Act – is the change in the vacatio legis period of the regulations. The first draft only provided for a 14-day deadline for the entry into force of the act, the current one is already 2 months. In addition, provisions have been introduced that allow entities that are primarily covered by the obligations under the Act to have a one-month deadline for carrying out these tasks. The total deadline for introducing the procedure will de facto be 3 months from the signing of the act. For other entities, the date remained unchanged – December 17, 2023.

The scale of the proposed changes encourages you to closely follow the progress of work. The final shape of the regulations may, however, be subject to further changes, as there are voices from the community pointing to new or further unadjusted defects in the act. It is also not known when the regulations will finally go to the first session of the Sejm and whether they will be referred to parliamentary committees.