Important now

Check our newest soultions in the scope of property tax, family foundations, R&D tax relief, B2B contracts and many more!  

Check our newest soultions in the scope of property tax, family foundations, R&D tax relief, B2B contracts and many more!  

Premiere of the Made in Poland Report 2024

Premiere of the Made in Poland Report 2024

Poland: A Prime Destination for Businesses Aiming to Contribute to Ukraine’s Recovery

Poland: A Prime Destination for Businesses Aiming to Contribute to Ukraine’s Recovery

ESG at ALTO – Ewa Solarz will head a new business line

ESG at ALTO – Ewa Solarz will head a new business line

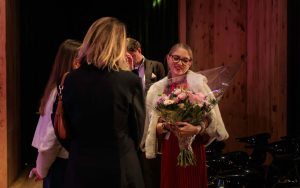
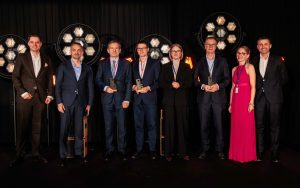
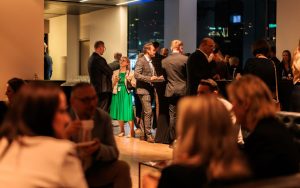
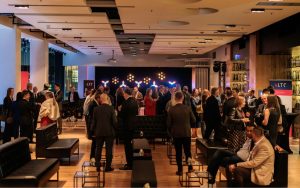
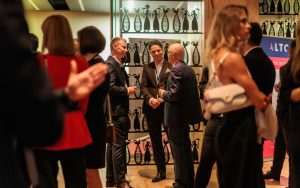
15 years on a shared journey: ALTO’s anniversary. Thank you for celebrating with us!

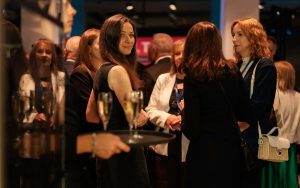
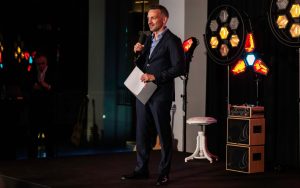
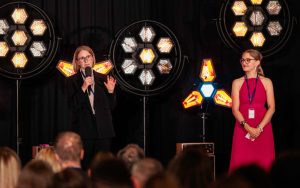
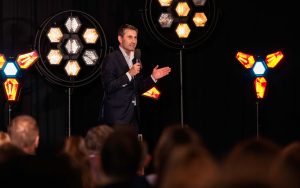
On 8 October 2026 we celebrated ALTO’s 15th anniversary. We met with our Clients at Concept 13 restaurant to thank them for years of working together and for their trust.

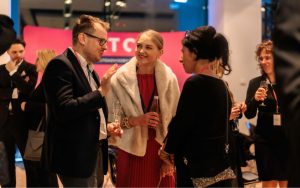
When planning the anniversary, one thing mattered to us most: we did not want it to be yet another formal event with a packed programme. We wanted to create an opportunity to meet and talk in a relaxed atmosphere, with no agenda and no glancing at the clock.

Day to day, our conversations with Clients are mostly about deadlines, regulations and projects. This time we could simply sit down together, talk without rushing and get to know each other better. A big thank you to everyone who found the time to join us that evening!

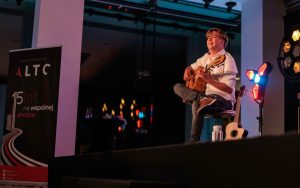
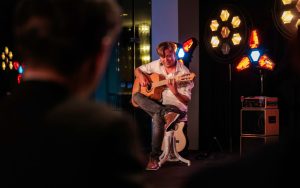
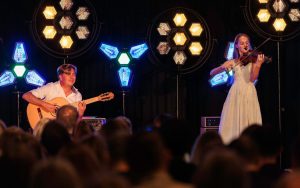
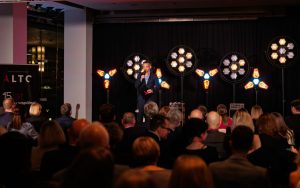
The programme included a short official part, refreshments and an artistic performance. The evening was graced by a concert by Thomas Zwijsen. If you would like to return to his music or discover it for the first time, we invite you to visit his YouTube channel: https://www.youtube.com/ThomasZwijsen

15 years is, above all, about people

An anniversary invites us to look back. When we think about these 15 years, what comes to mind is not numbers but people: problems we solved together, harder moments we came through side by side, and relationships that over time became more than just business. ALTO is where it is today largely thanks to the trust of our Clients. And with three companies, we have been working together since the very beginning!

For this trust, for the projects we have shared and for every conversation, we sincerely thank you. We hope the coming years will bring many opportunities to keep working together and also, perhaps most of all, to meet at events like this one.

We invite you to take a look at a small photo gallery from the evening.


Photos by: Rafał Warszawski Watch Your Business

ALTO once again recommended among Poland’s leading tax firms in ITR World Tax

A few weeks after being named “Poland Transfer Pricing Advisory Firm of the Year” at the ITR Europe Tax Awards, ALTO has received another distinction. In this year’s edition of the ITR World Tax ranking, we have retained our “Recommended firm” status and our position in three practice areas. Eight of our experts have also received individual recognition.


ALTO’s position in ITR World Tax

ITR World Tax is one of the most widely recognised international rankings of tax advisory firms. This year, ALTO has been ranked in the following categories:

  • Transfer Pricing: Tier 2
  • General Corporate Tax: Tier 3
  • Tax Controversy: Tier 3

Retaining our position in the ranking confirms that our clients can rely on consistent quality of advice, whether in day-to-day tax matters, transfer pricing or disputes with the tax authorities.


ALTO experts recognised

This year, 8 ALTO experts received individual recognition, one more than last year. Two of these distinctions are entirely new: they went to Aneta Grzyb and Mateusz Paliszewski from our transfer pricing team. This is particularly meaningful to us, as it coincides with this year’s ITR Europe Tax Awards win in TP.


What this means for our clients

For us, recognition in ITR World Tax is above all a reflection of the trust our clients place in us. Thank you for every case and project we have worked on together. We also congratulate our recognised experts and the teams who build ALTO’s position every day.

If you would like to speak with our experts about transfer pricing, corporate tax or tax disputes, get in touch with us.

R&D relief, EU grants and the Polish Investment Zone (PIZ): a guide to combining support

Using preferences in parallel and the prohibition of double funding

Yes, the R&D relief, EU grants and the tax exemption under the Polish Investment Zone can be combined. There is one key condition: the same cost amount cannot be settled twice as the basis for different preferences. This is what the prohibition of double funding, often referred to as double dipping, means in practice. It is not a ban on using several forms of support, but a ban on “counting the same zloty” in several calculations at once.

Each of these instruments works differently. The R&D relief allows an additional deduction from the tax base of costs incurred on research and development activity. An EU or national grant usually finances or reimburses specific expenses in a project. The Polish Investment Zone, in turn, provides an income tax exemption for income earned from the activity specified in the support decision, up to the available public aid limit.

Mechanism How it works Legal basis Is it public aid?
R&D relief Additional deduction of qualifying costs from the tax base Art. 18d of the CIT Act, Art. 26e of the PIT Act As a rule, no, with exceptions concerning, among others, research and development centres and the cash refund
EU or national grant Financing or reimbursement of specific project expenses Funding agreement, call rules, programme regulations Usually yes, depending on the programme and the basis on which support is granted
PIZ exemption Income tax exemption for income from activity covered by the support decision, up to the aid limit Act on supporting new investments, Art. 17(1)(34a) of the CIT Act, Art. 21(1)(63b) of the PIT Act Yes, as regional investment aid


This is why these instruments can operate side by side. The problem only arises when one specific cost is meant to increase the grant amount, reduce the tax base under the R&D relief and affect the calculation of exempt income in the PIZ at the same time.

In the CIT Act, this principle is visible above all in two provisions. Art. 18d(5) of the CIT Act states that qualifying costs may be deducted if they have not been reimbursed to the taxpayer in any form or deducted from the income tax base. The same restriction appears in Art. 26e(5) of the PIT Act. Art. 18d(6) of the CIT Act adds a special rule for taxpayers using a zone exemption or a support decision: only those qualifying costs that are not taken into account when calculating tax-exempt income may be deducted under the R&D relief. For PIT taxpayers, Art. 26e(6) of the PIT Act performs the same function.

It is also worth getting the terminology right. An “eligible cost” in a grant project is not the same as a “qualifying cost” under the R&D relief. The first term follows from the call rules, the funding agreement and the programme rules. The second follows from the CIT Act or the PIT Act. The same expense may be eligible in a grant project but not meet the conditions of the R&D relief. The reverse is also possible: a cost meets the tax conditions but is not eligible under a given grant programme.

From the public aid perspective, one more distinction is important. The standard R&D relief is, as a rule, not public aid. The exceptions concern, among others, selected preferences for research and development centres and the cash refund of the unused relief, which constitutes de minimis aid. In practice, this means that when a grant is combined with the R&D relief in the usual way, the biggest risk is usually not exceeding the public aid limit itself, but the tax prohibition on deducting a cost that has already been reimbursed to the taxpayer.


EU grants and qualifying costs in the R&D relief: what can be safely deducted?

If a cost has been covered by a grant, that part of the cost should not be deducted under the R&D relief. If the grant financed only part of the expense, the part financed from the company’s own funds may be included in the relief, provided it meets the other conditions of the relief. This is the basic rule arising from Art. 18d(5) of the CIT Act and Art. 26e(5) of the PIT Act.

Example: a company incurred PLN 1 million in salary costs for its R&D team. The project was co-financed at 60%, and the company covered the remaining 40% itself. The full PLN 1 million should not be taken into the R&D relief calculation. The starting point is the company’s own share, i.e. PLN 400,000. Only then is the appropriate deduction limit for the given cost category applied to that amount.

This approach is confirmed by interpretative practice. In an individual interpretation of 2 March 2026, 0111-KDIB1-3.4010.6.2026.2.ZK, concerning equipment partly financed with funds from the Agency for Restructuring and Modernisation of Agriculture (ARiMR), the Director of National Tax Information (KIS) accepted the deduction under the R&D relief of only the part of the expense that was not covered by the co-financing.

It may also happen that a company first deducts a cost under the R&D relief and only later receives a grant or reimbursement. In such a situation, it is not always necessary to go back to the historical year and correct the original relief settlement. Art. 18d(5a) of the CIT Act requires the tax base to be increased or the loss to be reduced in the return for the year in which the cost was reimbursed. An analogous rule applies in PIT under Art. 26e(5a).

The practical conclusion is simple: a grant does not cancel the right to the R&D relief, but it requires precise separation of costs. The company should know what part of the expense was covered by the grant, what part was actually incurred from its own funds, and what part of that own amount meets the conditions of an R&D qualifying cost.


How to settle depreciation of fixed assets financed with a grant?

For fixed assets and intangible assets used in R&D, the purchase invoice itself is generally not deducted. What goes into the R&D relief are depreciation write-offs, i.e. the part of the value of the fixed asset or intangible asset that is settled for tax purposes in a given year. For ordinary taxpayers, passenger cars, structures, buildings and premises constituting separate property are excluded from qualifying costs. Different rules may apply to taxpayers with research and development centre status.

For assets financed with a grant, several provisions must be combined. Art. 16(1)(48) of the CIT Act excludes from tax-deductible costs the part of depreciation write-offs corresponding to expenses reimbursed to the taxpayer. In PIT, an analogous mechanism follows from Art. 23(1)(45) of the PIT Act. At the same time, Art. 18d(3k) of the CIT Act and Art. 26e(3k) of the PIT Act provide that these exclusions do not apply to qualifying costs constituting depreciation write-offs.

This does not mean, however, that the grant-funded part of depreciation can automatically be deducted under the R&D relief. The general rule still applies that a cost reimbursed to the taxpayer should not be deducted under the relief. Therefore, the safest approach is to separate the part financed by the grant from the company’s own part and to take into account the actual use of the asset in R&D activity.

Example: a company bought a device for PLN 2 million, half of which was financed by a grant. The annual depreciation write-off is PLN 200,000. The device is used for R&D 70% of the time. A cautious calculation of the qualifying cost looks like this: PLN 200,000 × 50% own share × 70% use in R&D = PLN 70,000. Only then is the appropriate deduction limit applied to that amount.

For larger amounts or more complex financing, it is worth considering applying for an individual interpretation. This part of the relief is more technical than salary or materials costs, because it requires simultaneously taking into account the depreciation rules, costs reimbursed to the taxpayer, the conditions of the R&D relief and the way the fixed asset is actually used.

If the grant is received only after depreciation has started, the timing of receipt of the funds is important. In case law concerning general tax-deductible costs, it is accepted that the effects of reimbursement of depreciation write-offs are, as a rule, settled in the period in which the taxpayer actually received the funds, rather than by automatically going back to earlier periods. This is confirmed, among others, by the resolution of the Supreme Administrative Court of 14 December 2015, II FPS 4/15, and the more recent judgment of the Supreme Administrative Court of 16 April 2026, II FSK 866/23. In the R&D relief itself, a similar effect follows directly from Art. 18d(5a) of the CIT Act and Art. 26e(5a) of the PIT Act.


The R&D relief and a support decision under the Polish Investment Zone

A PIZ support decision in itself does not exclude the R&D relief. The CIT Act expressly provides for a situation in which a taxpayer simultaneously uses a zone or PIZ exemption and the R&D relief. The condition is that costs taken into account in calculating exempt income are not settled under the R&D relief.

For CIT taxpayers, this follows from Art. 18d(6) of the CIT Act. The provision refers to the exemptions under Art. 17(1)(34) and (34a) of the CIT Act, i.e. special economic zones and PIZ support decisions. For PIT taxpayers, Art. 26e(6) of the PIT Act has an analogous meaning, in conjunction with the exemptions under Art. 21(1)(63a) and (63b) of the PIT Act.

In practice, therefore, the problem is not simply having a support decision. It must be checked whether the company is actually already using the exemption and whether a specific R&D cost has been taken into account in calculating exempt income. If the cost relates to taxable activity or does not affect the calculation of exempt income, it can still be analysed for the R&D relief. If, however, the same cost has already been included in the calculation of exempt income under the PIZ, deducting it again under the R&D relief would be incorrect.

This approach is confirmed by individual interpretations. In the interpretation of 14 May 2026, 0114-KDIP2-1.4010.94.2026.2.JF, the Director of KIS agreed that a taxpayer may use the R&D relief before starting to use the exemption, and then combine the R&D relief with the exemption, provided that it settles under the relief costs not taken into account in exempt income. A similar approach can be seen in earlier interpretations, including 0114-KDIP2-1.4010.209.2022.3.MW and 0111-KDIB1-3.4010.302.2023.1.JKU.

Case law concerning special economic zones is also worth using. In its judgment of 9 September 2021, II FSK 724/21, the Supreme Administrative Court confirmed that the law does not preclude a taxpayer carrying out zone activity from using the R&D relief, provided that the same costs are not settled twice. The earlier stage of this case was the judgment of the Provincial Administrative Court in Rzeszów of 18 February 2021, I SA/Rz 32/21. These judgments concern SEZs, not PIZ support decisions directly, but they are important because Art. 18d(6) covers both exemption regimes.


Settling R&D costs from exempt activity and taxable activity

The most important thing is a proper separation of costs. The mere fact that a project is located at a site covered by a support decision does not yet determine that the cost is excluded from the R&D relief. What matters is whether the cost was taken into account in calculating exempt income.

In practice, three typical situations can be distinguished. First: the R&D team works on a product, technology or process used exclusively in taxable activity. In such a case, the support decision should not in itself block the R&D relief. Second: the R&D team works directly for the activity covered by the exemption, and the costs are included in the calculation of exempt income. In that case, Art. 18d(6) of the CIT Act or Art. 26e(6) of the PIT Act blocks their deduction a second time. Third: the project is mixed and serves both taxable and exempt activity. In that case, a rational, documented allocation key is needed.

In none of these situations is a general statement that the cost “does not relate to exempt activity” sufficient. The company should have records that make it possible to trace from the source document, e.g. an invoice, a payroll or a depreciation document, to a specific project, employee, fixed asset, usage proportion and the final amount reported under the R&D relief.

A good way of thinking about this is two parallel layers: the records of R&D qualifying costs and the calculation of exempt income under the PIZ. If these layers are kept separate, it is easier for the company to show that it is not settling the same amount twice. If they are mixed, the risk of a dispute with the authority increases.


How to safely plan the mix of innovation funding in a company?

It is best to plan the split of funding already at the project budget stage, not only at the annual CIT or PIT settlement. This way, the same invoice, salary or depreciation write-off does not accidentally end up in several calculations at once.

Below are a few typical situations:

  • An R&D project is partly financed by a grant: the company incurs PLN 1 million in materials costs, of which PLN 600,000 is reimbursed. At most PLN 400,000 of own costs may be included in the R&D relief, provided they meet the definition of qualifying costs.
  • A company buys a device for its R&D laboratory and finances half of it with a grant. What counts under the R&D relief are depreciation write-offs, not the capital expenditure itself, taking into account the share of own financing and the actual use of the device in R&D.
  • A company has a PIZ support decision but carries out R&D projects unrelated to its exempt activity. Their costs may be included in the relief if they are not taken into account in calculating exempt income.
  • R&D work concerns production covered by the PIZ exemption, and the costs affect exempt income. The same costs should not be settled under the R&D relief, unless the part relating to taxable activity can be reliably separated.


At a glance:

Situation Can the cost be included in the R&D relief?
Cost fully financed by a grant No, because it was reimbursed to the taxpayer
Cost partly co-financed Yes, but only in the part covered from own funds and meeting the conditions of the relief
Cost relates to taxable activity, despite holding a PIZ support decision Yes, if it was not taken into account in calculating exempt income
Cost taken into account in calculating PIZ exempt income No, it should not be deducted a second time under the R&D relief
Mixed cost, partly related to exempt activity and partly to taxable activity Yes, but only in the part attributable to taxable activity, according to a documented allocation key


The safest funding mix is not “putting costs everywhere”, but a cost map. For each significant expense, it should show: the source of funding, grant eligibility, eligibility for the R&D relief, the link to PIZ exempt activity, the usage proportion and the final deduction amount.

Non-tax documents must also be remembered. For grants, the call rules, the funding agreement, the catalogue of eligible costs and the project durability rules must be checked. For the PIZ, the content of the support decision, the scope of activity covered by the decision, the location of the investment, the moment the exemption started to be used and the extent to which the public aid limit has been used must be checked. The standard R&D relief is, as a rule, not public aid, but the restrictions under Art. 18d(5) and (6) of the CIT Act and Art. 26e(5) and (6) of the PIT Act still apply. Where de minimis aid or regional investment aid is involved, limits and aid cumulation rules must also be monitored.

See also: the R&D relief can be combined not only with grants and the PIZ. If a company commercialises the results of R&D work in the form of intellectual property rights, it is worth checking the combination of the R&D relief with the IP Box relief. Companies planning investments in digitalisation and automation may also look at the article on what the tax on excess profits from digitalisation has in common with the R&D relief.

How ALTO can help: before a company starts settling costs in several places at once, it is worth checking whether the split between the grant, the R&D relief and the PIZ is consistent and documented. ALTO helps design the project cost map, check which expenses can safely be included in the R&D relief and which have already been “consumed” by the grant or the PIZ exemption, and prepare records that will stand up to questions from the tax office. See how we can help your company.


FAQ: Frequently asked questions about combining the R&D relief with grants and the PIZ


Can the R&D relief be combined with an EU grant?

Yes, but only for the part of the cost that was not covered by the grant or reimbursed to the taxpayer in another form. The same amount cannot be both financed by a grant and deducted under the R&D relief.


Can a company with a PIZ support decision use the R&D relief?

Yes. In CIT, this is allowed by Art. 18d(6) of the CIT Act, and in PIT by Art. 26e(6) of the PIT Act. The condition is that qualifying costs cannot be taken into account in calculating tax-exempt income.


What is double funding, or double dipping?

It is a situation in which the same cost amount is used more than once, e.g. as an expense covered by a grant, an element of the PIZ exempt income calculation and a qualifying cost deducted under the R&D relief. Tax law does not allow such double settlement.


How to settle depreciation of a machine partly financed by a grant?

The safest approach is to include in the relief only the part of the depreciation write-off corresponding to own financing and the actual use of the machine in R&D. Neither the entire write-off nor the purchase expense itself is deducted if the machine is a fixed asset.


What if we receive the grant after deducting the cost under the R&D relief?

The previously deducted amount must be settled in the return for the year in which the company received the reimbursement: by increasing the tax base or reducing the loss. This follows from Art. 18d(5a) of the CIT Act and Art. 26e(5a) of the PIT Act.


Sources

  • Art. 18d(1), (3), (3k), (5), (5a), (6), (7) and (8) of the CIT Act; correspondingly Art. 26e of the PIT Act.
  • Art. 16(1)(48) and Art. 17(1)(34) and (34a) of the CIT Act; correspondingly Art. 23(1)(45) and Art. 21(1)(63a) and (63b) of the PIT Act.
  • Act of 10 May 2018 on supporting new investments, Journal of Laws 2025, item 469.
  • Ministry of Finance, “Investor’s tax guide. Reliefs and incentives”, 2026.
  • Individual interpretation of the Director of KIS of 2 March 2026, 0111-KDIB1-3.4010.6.2026.2.ZK.
  • Individual interpretation of the Director of KIS of 14 May 2026, 0114-KDIP2-1.4010.94.2026.2.JF.
  • Individual interpretations of the Director of KIS: 0114-KDIP2-1.4010.209.2022.3.MW and 0111-KDIB1-3.4010.302.2023.1.JKU.
  • Judgment of the Supreme Administrative Court of 9 September 2021, II FSK 724/21.
  • Judgment of the Provincial Administrative Court in Rzeszów of 18 February 2021, I SA/Rz 32/21.
  • Resolution of the Supreme Administrative Court of 14 December 2015, II FPS 4/15.
  • Judgment of the Supreme Administrative Court of 16 April 2026, II FSK 866/23.


Article updated: September 2026.

Claiming the R&D relief retroactively: how to recover overpaid tax through a correction?

Can the R&D relief be claimed for previous years?

Yes, provided that the given year is not yet time-barred and the company already met the conditions for the relief at that time. A correction does not create a right to the relief “after the fact”. It only amends an earlier settlement in which the taxpayer was entitled to the deduction but did not use it.

The basis for the deduction is Art. 18d of the CIT Act and, for PIT taxpayers, Art. 26e of the PIT Act. The right to amend a previously filed return, in turn, follows from Art. 81 of the Tax Ordinance Act. In practice, this means filing a corrected CIT-8 return together with the CIT/BR attachment, or a corrected version of the relevant PIT return, for example PIT-36 or PIT-36L, together with the PIT/BR attachment.

The most important thing, however, is that the company can show that its historical projects were in fact research and development activity within the meaning of the law. This means creative activity comprising scientific research or development work, carried out systematically and aimed at increasing the stock of knowledge or using knowledge to create new applications. For CIT, this follows from Art. 4a(26) to (28) of the CIT Act, and for PIT, from Art. 5a(38) to (40) of the PIT Act. A decision taken today that “we want to use the relief” is not enough if there are no real projects from the given year behind the deduction.

There are also two limitations that are easy to forget when the topic is presented from a sales perspective.

First, a qualifying cost may not have been reimbursed to the taxpayer in any form or previously deducted from the income tax base. This follows from Art. 18d(5) of the CIT Act and Art. 26e(5) of the PIT Act. So if the company received a grant, a reimbursement or other funding covering part of the project costs, the reimbursed part should, as a rule, not be included in the R&D relief.

Second, companies using special economic zone exemptions or support decisions under the Polish Investment Zone may include in the R&D relief only those costs that were not taken into account when calculating tax-exempt income. This follows from Art. 18d(6) of the CIT Act. Operating in a special economic zone (SEZ) or the Polish Investment Zone (PIZ) therefore does not in itself exclude the R&D relief, but it requires a very precise separation of the costs of taxable and exempt activity.


How many years back can the R&D relief deduction be claimed?

The slogan “5 years back” is convenient, but not entirely precise. The five years are not counted from the date the correction is filed. What matters is when the tax liability for the given year becomes time-barred.

Under Art. 70 § 1 of the Tax Ordinance Act, a tax liability becomes time-barred after five years, counted from the end of the calendar year in which the tax payment deadline fell. This means that we look not only at the year to which the correction relates, but also at the year in which the tax payment deadline fell.

CIT tax year Tax payment deadline Limitation period ends at the end of
2020 2021 2026
2021 2022 2027

In other words, in September 2026, with a standard tax year, a correction for 2020 and 2021 can still be analysed, but 2020 must be closed before the end of 2026.

Therefore, the safe sentence for the article is: the years that are not yet time-barred can be corrected. Which year is still open depends on the tax payment deadline for a specific year, and in the case of a non-standard tax year or special events, this must be checked separately.

It must also be remembered that the limitation period may be suspended or interrupted. For example, Art. 70 § 6(1) of the Tax Ordinance Act provides for the suspension of the limitation period in connection with the initiation of proceedings concerning a fiscal offence or a fiscal petty offence, if the taxpayer has been notified of this in accordance with the Tax Ordinance Act. In practice, this means that “five years” does not always work like a simple countdown.

There is one more important point: correcting the return alone is not enough if the company wants to recover overpaid tax. An application for a determination of overpayment must also be filed before the limitation period expires. This follows from Art. 79 § 2 of the Tax Ordinance Act. If the taxpayer files the application too late, even a substantively correct correction may not translate into a refund.


What does the procedure for correcting a CIT/PIT tax return look like?

In practice, there are two stages: first, the right to the relief must be reconstructed and documented, and only then are the correction and the application for a determination of overpayment filed. Most of the work usually lies not in correcting the form itself, but in preparing material that will show the tax office that the deduction is justified.

Preparing retrospective records of R&D projects and costs

The law requires R&D costs to be separately identified in the taxpayer’s records. For CIT, this follows from Art. 9(1b) of the CIT Act, and for PIT, from Art. 24a(1b) of the PIT Act. However, there is no single statutory template for the documentation. The law does not impose a specific form of records.

In practice, auxiliary records, for example a spreadsheet, may be sufficient if they make it possible to trace the deduction amount unambiguously back to the source documents. They should show which costs, in which year, in which category and for which project were treated as qualifying costs.

Greater caution is needed when a company wants to reconstruct its records after several years. For taxpayers keeping a tax book of revenue and expenses (PKPiR), there are favourable interpretations on completing column 16 of the PKPiR by way of correction. In interpretation 0115-KDIT3.4011.120.2026.2.PS, the authority held that entering R&D costs in column 16 of the book, in the form of PKPiR corrections for the relevant periods, meets the record-keeping conditions required to use the R&D relief. Similarly, interpretation 0115-KDIT3.4011.831.2024.2.PS concerned corrections for 2019 to 2023.

However, this should not be turned into too broad a rule. These interpretations are an important argument, but they do not mean that every table prepared years later will be accepted. The safe thesis is this: the records can be reconstructed, but they must be based on real data from the period in which the project was carried out. The authority will check whether the costs can be linked to source documents, the team’s work and the actual course of the project, not just to the final refund amount.

This risk is well illustrated by the non-final judgment of the Provincial Administrative Court in Łódź of 17 June 2025 (I SA/Łd 208/25). The company presented project sheets, working time records, payroll documentation and cost summaries, but the court accepted the authority’s assessment that some of the documents may have been created only for the purposes of the overpayment application. The problems included, among others, missing dates, authors and signatures. The conclusion for taxpayers is practical: documentation prepared after the fact must be based on traces from the given year, such as schedules, technical documentation, repositories, project correspondence, test reports, working time records, payrolls, invoices and accounting entries.

Good R&D records should therefore not be just a table of costs. They should answer several questions: what the purpose of the project was, what the creative element consisted of, what the technical or technological uncertainty was, who took part in the work, which costs were allocated to the project, and how the proportion of involvement in R&D was calculated.

Employee costs and deduction limits

In many companies, personnel costs make up the largest part of the R&D relief. Art. 18d(2)(1) of the CIT Act and Art. 26e(2)(1) of the PIT Act allow employees’ remuneration and contributions financed by the payer to be included in the proportion that the time spent on R&D activity bears to the employee’s total working time in a given month. Similar rules apply to remuneration under contracts of mandate and contracts for specific work, under Art. 18d(2)(1a) of the CIT Act and Art. 26e(2)(1a) of the PIT Act.

Type of cost Deduction amount from 2022
Employee costs and civil law contracts related to R&D (other than research and development centres) 200%
Other qualifying costs 100%, unless special rules for research and development centres apply

For corrections for earlier years, however, the limits in force in the corrected year must be applied. This is important, because a correction for 2020 or 2021 cannot automatically use limits that came into force later.

The general interpretation of the Minister of Finance of 13 February 2024 (DD8.8203.1.2021) confirms a favourable approach to remuneration for periods of justified absence. Remuneration for holidays, sick leave or other justified absences may be included in qualifying costs in the appropriate proportion, provided that the other conditions of the relief are met.

Case law on management staff is also favourable for taxpayers. The judgment of the Supreme Administrative Court of 21 March 2023 (II FSK 2217/20) confirms that the remuneration of persons performing managerial or supervisory functions cannot automatically be excluded from qualifying costs if they actually participate in R&D activity or supervise R&D work. What counts is the actual scope of duties, not the job title itself.

In turn, the judgment of the Supreme Administrative Court of 21 November 2024 (II FSK 226/22) is important for bonuses and awards paid for periods longer than one month. It shows that the calculation must take into account not only the payment itself, but also the way the proportion of involvement in R&D is determined. For larger corrections for previous years, personnel costs therefore often require a separate, detailed calculation.

Filing an application for a determination of tax overpayment with the tax office

If the correction reduces the tax due, the taxpayer should file an application for a determination of overpayment. The basis is Art. 75 of the Tax Ordinance Act. Under Art. 75 § 3 of the Tax Ordinance Act, where the taxpayer was required to file a tax return or declaration, the corrected return is filed together with the application for a determination of overpayment.

In practice, the full set of documents should include: the corrected CIT-8 or relevant PIT return, the CIT/BR or PIT/BR attachment, the application for a determination of overpayment, and a justification showing why the relief was available in the corrected year. The justification itself is not always formally required for every correction, but it is very much needed for the R&D relief and an overpayment refund application. Without it, the tax office will probably ask for additional explanations.

The refund deadline must be described with caution. Art. 77 § 1(6)(a) of the Tax Ordinance Act provides for the refund of an overpayment within two months of the date of filing the application together with the corrected return, but not earlier than three months from the date of filing the original return or declaration. This is a good argument for the slogan “a quick cash injection”, but it is not a guarantee of payment in every case.

If the correction raises doubts, the authority may conduct overpayment proceedings, request documents and issue a decision. In such a situation, the refund may come later, and if the authority is late, interest on the overpayment under Art. 78 of the Tax Ordinance Act may be relevant.

Art. 76 of the Tax Ordinance Act must also be remembered. An overpayment does not always go directly to the taxpayer’s bank account. It is first offset ex officio against tax arrears, interest, reminder costs and current tax liabilities. Only if there are no such amounts due does the tax office refund the money to the taxpayer. In practice, “hard cash” may therefore mean either a bank transfer or a reduction of existing liabilities to the tax authorities.


Does a return correction with the R&D relief automatically trigger a tax audit?

No. There is no provision requiring an audit to be initiated merely because the taxpayer has filed a correction with the R&D relief. This is important, because many entrepreneurs fear that simply applying for an overpayment will automatically “bring on an audit”.

This does not mean, however, that the tax office will not ask questions. With a correction for previous years and an overpayment refund application, taxpayers must expect verification activities or overpayment proceedings. Art. 272 of the Tax Ordinance Act allows the authorities to check the timeliness of filing returns, the formal correctness of documents, and to establish the facts to the extent necessary to confirm consistency with the documents presented. Art. 274a § 2 of the Tax Ordinance Act allows the authority to request explanations from the taxpayer if it has doubts about the correctness of the return.

In practice, the tax office’s questions usually concern which projects were treated as R&D, who worked on them, how working time was calculated, which costs were included as qualifying costs, whether the costs were reimbursed to the taxpayer, and whether the amounts in CIT/BR or PIT/BR follow from the books. The older the year and the higher the overpayment amount, the more important consistent documentation becomes.

Art. 79 § 1 of the Tax Ordinance Act must also be taken into account. Proceedings for a determination of overpayment cannot be initiated while tax proceedings, a tax audit or a customs and tax audit are in progress with respect to the same tax liabilities. So if the company is already being audited for a given year and the same scope, the simple path of a correction with an overpayment application may be temporarily unavailable. At the same time, Art. 81b of the Tax Ordinance Act provides for the suspension of the right to correct for the duration of tax proceedings or a tax audit in the scope covered by those proceedings or that audit.


When does a retroactive settlement pay off? Case study and financial benefits

Claiming the R&D relief retroactively pays off when the company actually carried out R&D projects, incurred qualifying costs, had income that allowed the deduction to be used, and paid tax that turns out to be overstated after the correction. In that case, the correction may translate into an overpayment and, after its verification, into a refund or an offset against liabilities.

Example: a company subject to CIT at the 19% rate identifies PLN 1 million of qualifying costs deductible at 100%. The potential tax benefit is approximately PLN 190,000. If these are employee costs incurred in a year in which the 200% limit applies, the deduction amount may increase to PLN 2 million, and the tax benefit to approximately PLN 380,000. This is, of course, an example based on simple figures, not a promise of a specific refund.

For CIT taxpayers using the 9% rate, the effect will be lower, because the R&D relief reduces the tax base, not the tax itself independently of the rate. For PIT taxpayers, the effect depends on the form of taxation, i.e. the progressive tax scale or the flat tax.

A correction does not always mean a cash refund. If the company had a loss in a given year or income lower than the available deduction, the unused part of the relief is settled over the following six tax years. This follows from Art. 18d(8) of the CIT Act and Art. 26e(8) of the PIT Act. In such a case, the correction may improve the tax position for the future, but it does not have to result in a transfer from the tax office now.

A separate mechanism is the direct refund of the unused relief under Art. 18da of the CIT Act and Art. 26ea of the PIT Act. It applies primarily to taxpayers starting a business and, in certain cases, also to the year immediately following the year in which the business was started. This is a narrower path, subject to additional conditions, not a standard procedure for every company claiming the relief retroactively.

Finally, one more reservation is worth adding. The R&D relief does not cover ordinary, routine improvements or the standard execution of orders without a creative element and without real technical or technological uncertainty. The judgment of the Supreme Administrative Court of 20 August 2024 (II FSK 595/24) shows that in projects carried out on behalf of a client, the authorities and courts may examine not only the level of costs, but also whether R&D activity actually took place in the project. Therefore, before the correction, both the costs and the nature of the projects themselves must be assessed.


How can ALTO Advisory help?

Before a company decides on a correction, it is worth checking whether the documentation from the years to be settled will stand up to questions from the tax office. It is not enough to confirm the amount the taxpayer would like to recover. It must also be shown that the projects met the definition of R&D activity, that the costs were properly separated, and that the calculation follows from the source documents.

ALTO Advisory helps verify whether historical projects actually meet the definition of research and development activity, prepare cost records based on documents from the given period, and draft the corrected return and the application for a determination of overpayment. See how we can help your company.


FAQ: Frequently asked questions about claiming the R&D relief retroactively

Can the R&D relief be claimed retroactively?

Yes, if the given tax year is not yet time-barred and the company already met the conditions for the relief at that time. A correction does not create a new right to the relief; it only amends an earlier settlement.

How many years back can the R&D relief be claimed?

It depends on when the tax for the given year becomes time-barred, not on the date the correction is filed. In September 2026, with a standard tax year, the years 2020 and 2021, among others, can still be analysed, although 2020 in principle closes at the end of 2026.

Is a separate application needed to recover the overpayment?

Yes. Correcting the return alone is not enough. The application for a determination of overpayment must be filed together with the corrected return.

Does a correction with the R&D relief always end in an audit?

No. There is no provision requiring an audit after a correction with the R&D relief. In practice, however, the tax office may ask questions as part of verification activities or overpayment proceedings.

Does a correction always result in a cash refund?

No. If the company had a loss or too little income, the unused relief is carried forward for the next six years. If an overpayment arises, the tax office may first offset it against arrears or current tax liabilities.


Sources

  • Art. 18d, 18da, 9(1b), 4a(26) to (28), 17(1)(34) and (34a) of the CIT Act (Journal of Laws 2026, item 554).
  • Art. 26e, 26ea, 24a(1b), 5a(38) to (40) of the PIT Act (Journal of Laws 2026, item 592).
  • Art. 70, 75, 76, 77, 78, 79, 81, 81b, 272, 274a of the Tax Ordinance Act (Journal of Laws 2026, item 622).
  • General interpretation of the Minister of Finance of 13 February 2024, DD8.8203.1.2021.
  • Individual interpretations of the Director of National Tax Information (KIS): 0115-KDIT3.4011.120.2026.2.PS, 0115-KDIT3.4011.831.2024.2.PS, 0114-KDIP3-2.4011.196.2022.6.MR, 0114-KDIP2-1.4010.65.2023.3.MR, 0111-KDIB1-3.4010.907.2022.3.ZK.
  • Judgment of the Supreme Administrative Court of 21 March 2023, II FSK 2217/20.
  • Judgment of the Supreme Administrative Court of 21 November 2024, II FSK 226/22.
  • Judgment of the Supreme Administrative Court of 20 August 2024, II FSK 595/24.
  • Judgment of the Provincial Administrative Court in Łódź of 17 June 2025, I SA/Łd 208/25 [non-final].

Article updated: September 2026.

JPK CIT correction: how to fix errors from the first reporting cycle? It is not too late

A JPK CIT correction, i.e. amending a successfully submitted JPK_KR_PD file, is possible when the original file was accepted by the Ministry of Finance system

If the system rejected the file, no effective submission has yet taken place, so there is nothing to correct. In such a situation, a correct file must be prepared and sent as an original submission. If the deadline has already passed, the matter requires additional assessment in terms of late submission of the books and possible voluntary disclosure (czynny żal).

In this article, we explain when a JPK_CIT correction is justified, how to prepare it technically and substantively, when correcting the file alone is not enough, and in which cases a CIT-8 correction or voluntary disclosure must be considered separately.


First JPK CIT file sent in a hurry? Why it is worth verifying the data submitted

The first JPK CIT reporting is worth verifying because the JPK_KR_PD file is not an ordinary tax return, but an electronic representation of the accounting books submitted to the tax authority. The authority may compare data from JPK_KR_PD with the CIT-8 return, the financial statements, JPK_VAT files and, ultimately, other electronically reported data, including data from structured invoices. An error in JPK_CIT does not always mean an error in the tax settlement itself, but it may increase the risk of questions, requests for explanations or verification activities.

Time pressure during the first reporting is the main reason why it is worth reviewing the file again after submission. During implementation, taxpayers simultaneously map the chart of accounts to tax tags, adapt their finance and accounting systems, test data exports and set rules for possibly splitting the file into parts. The JPK_KR_PD file should cover all book entries for the reporting period. If the books are kept in more than one system, the data must be combined into a complete picture of the books, without gaps, duplicates or omitted accounts.


When should a JPK CIT correction be submitted? Different consequences of technical and substantive errors

A JPK CIT correction is submitted when the original file was successfully accepted by the Ministry of Finance system, and after submission formal errors, amount errors or other substantive irregularities were identified in it. A distinction must be made between an error in a file that has already been accepted and a technical error that prevented the file from being submitted. These are two different situations and require different actions.

Type of error What it involves What needs to be done
Technical error (non-compliance with the schema) The file did not pass validation and the Ministry of Finance system did not accept it, so nothing was effectively submitted Correct the file and send it again as an original submission, with the value “1” in the CelZlozenia field
Substantive error An irregularity in a file that has already been successfully accepted, e.g. an incorrect reporting period, omission of part of the books, incorrect balances or tax tags Submit a correction with the value “2” in the CelZlozenia field

Technical errors, i.e. non-compliance with the schema, are not a correction

If the file did not pass validation and the Ministry of Finance system did not accept it, there is no question of a correction yet, because nothing was effectively submitted. The file must be corrected and sent again as an original submission.

Such errors include, among others, missing mandatory fields, non-compliance with the XSD, i.e. the formal template of the XML structure, an incorrect electronic signature, or the absence of valid authorisation of the person signing the file on behalf of the taxpayer. The corrected file, provided that it was not originally accepted, should be marked as the first submission, i.e. with the value “1” in the CelZlozenia field. If the submission deadline has already passed, the problem is not a correction, but late submission of the books. In such a case, the risk of fiscal penal liability and the justification for filing a voluntary disclosure should be assessed separately.

Substantive errors, i.e. incorrect tags, an incomplete picture of the books or incorrect data

A substantive error is an irregularity in a file that has already been successfully accepted. It may concern, for example, an incorrect reporting period, an incorrect tax office code, incorrect taxpayer identification data, omission of part of the books, incorrect balances or turnover, inconsistency between synthetic and analytical accounts, or incorrect tax tags assigned to accounts. Errors of this kind may justify a correction, because the file already exists in electronic circulation as submitted, but its content does not correctly reflect the books.

One reservation is particularly important for the first reporting. The Regulation of the Minister of Finance of 16 August 2024 on additional data for accounting books (Journal of Laws 2024, item 1314), as amended by the Regulation of the Minister of Finance and Economy of 15 December 2025 (Journal of Laws 2025, item 1828), provides for transitional simplifications. For the tax year beginning after 31 December 2024 and before 1 January 2026, and in the case of companies without legal personality for the corresponding financial year, the books may omit some of the additional data, in particular the counterparty’s tax identification number (NIP), data on fixed assets and intangible assets, and data from the RPD node, i.e. information on differences between the accounting result and the tax result. The absence of this data for the first reporting year should therefore not in itself be treated as a typical error requiring a correction, provided that the taxpayer falls within the scope of the transitional provision.

Precision is needed, however. The simplification applies only to the specified additional data. It does not mean a general exemption from the obligation to reflect the books faithfully and completely to the extent required for a given year. As a rule, for the first reporting year, the correct presentation of the books and the proper assignment of account identification tags are of key importance. However, special rules must be taken into account for taxpayers preparing financial statements in accordance with IFRS/IAS, for whom the exemption from the obligation to supplement the books with additional data in the form of account identification tags has been extended until 1 January 2028.

It is also worth remembering that the optional status of a field in the logical structure does not always mean it may be left blank at will. If a given field is technically optional, but in a given situation a value resulting from the books or from the requirements of the structure should be assigned to it, failure to complete it may be a substantive error.


How to submit a JPK CIT file correction step by step?

A JPK_KR_PD correction involves resubmitting all data for the corrected period, not sending only the difference compared to the original file. Therefore, the first step is not to fix one field in the XML, but to determine what scope of data the new, complete file must cover.

Confirm whether the original submission was successful

Check the processing status of the file and download the official confirmation of receipt (UPO). If the file was rejected, the matter does not concern a correction, but a correct original submission.

Determine the scope of the correction

For an annual file, the correction covers the full scope of data of the original file for the given tax or financial year. For partial files, split into shorter periods, the correction should cover the same partial period to which the original file related. If the error affects subsequent partial periods, those later parts must also be corrected, maintaining full continuity without gaps or duplicates.

Correct the data at source

A correction should not be a manual modification of the final XML file detached from the books. It should result from correcting the data in the finance and accounting system or in the layer that transforms the data into JPK. This matters for evidential purposes, because JPK_KR_PD is an electronic representation of the books and should remain consistent with them.

Generate the file in the structure appropriate for the corrected period and mark the purpose of submission as a correction

In the JPK_KR_PD structure, the CelZlozenia field is used to indicate whether the file is being submitted for the first time or as a correction. For a correction, the value provided for corrections, i.e. “2”, must be used. Before submission, the current version of the schema, the information brochure and Ministry of Finance announcements should be checked, because if the structure changes, it must be verified which version MF allows for corrections of a given period.

Verify the file in two stages before submission

First, a technical validation should be carried out: compliance with the XSD, correctness of the signature, validity of the signatory’s authorisation, technical limits of the submission channel, and compliance with the requirements of the API or the Klient JPK WEB application. Next, a substantive validation should be carried out: consistency with the books, completeness of accounts, correctness of balances, mapping of tax tags, continuity of periods and the relationship to the CIT-8 return.

Send the correction and keep documentation of the decision

It is worth documenting internally why a given error required a correction, which source data confirm the correct version, and whether the error affected the CIT-8. There is currently no standard separate form for justifying a JPK_CIT correction, but an internal decision trail may be of significant importance if the authority raises questions later.

Whether a JPK_CIT correction entails a correction of the CIT-8 return requires a separate decision. If the error concerned only technical or formal data or the way data was presented in the file, and the CIT-8 return correctly reported income, loss, the tax base and the tax, a JPK_KR_PD correction may be sufficient. If, however, the error affects taxable revenue, tax-deductible costs, loss, income, the tax base or the tax due, a JPK correction alone does not remove the effect on the settlement. In that case, a correction of the return under Art. 81 of the Tax Ordinance Act, payment of the tax arrears and interest, and possibly a voluntary disclosure must be considered separately.

Under the current legal framework, a tax return is corrected by filing a corrective return, which follows from Art. 81 § 2 of the Tax Ordinance Act. However, the rules applicable to corrections of tax returns should not be automatically transferred to a JPK_KR_PD correction. JPK_KR_PD is a transfer of books in a logical structure, not a CIT-8 return. Therefore, in practice, two levels must be separated: the correction of the JPK_KR_PD file and a possible correction of the CIT-8 return if the error affects the tax settlement.

It is also worth monitoring planned changes. In 2026, a draft act amending the Tax Ordinance Act and certain other acts, numbered UDER111, was published in the List of Legislative and Programme Work of the Council of Ministers. The draft is intended to standardise the rules for correcting electronically submitted tax books and move them to the general provisions of the Tax Ordinance Act. Until the changes are enacted and enter into force, the currently applicable provisions and the MF explanations on JPK_KR_PD should be relied upon.


JPK CIT errors and sanctions: will a correction protect against a penalty?

A correction submitted on the taxpayer’s own initiative may reduce the risk of liability, but it is not an automatic “amnesty” and does not replace voluntary disclosure if an act has already been committed that may constitute a fiscal petty offence or a fiscal offence. A JPK_CIT correction and voluntary disclosure are two different legal instruments.

Legal basis

The basis for sanctions is Art. 61a of the Fiscal Penal Code. Under this provision, anyone who, contrary to their obligation, fails to submit books to the competent tax authority or submits unreliable books is subject to a fine of up to 240 daily rates. In a case of lesser significance, the act constitutes a fiscal petty offence. This milder sanction also applies to anyone who submits books late or submits defective books.

What are unreliable books?

Unreliable books are books that do not reflect the actual state of affairs, for example with incorrect amounts or omitted events. Defective books are books kept in breach of the regulations, even if their content need not be false in an economic sense. In the context of JPK_KR_PD, the risk may therefore concern both material amount errors and serious formal or technical breaches.

3 situations with potential sanctions

In practice, the risk of sanctions may arise in three situations.

  1. When JPK_CIT was not successfully submitted at all, for example because the MF system rejected the file and the taxpayer did not resubmit it before the deadline.
  2. When the file was successfully submitted but is unreliable, because it does not correspond to the actual state of the books.
  3. When the file is defective, i.e. it breaches formal or technical requirements.

Not every technical or formal error will automatically lead to liability, but every material error requires assessment under Art. 61a of the Fiscal Penal Code.

Voluntary disclosure in JPK CIT

Voluntary disclosure is a separate instrument under Art. 16 of the Fiscal Penal Code, not an automatic effect of the correction itself. It requires notifying the authority of the commission of a prohibited act, disclosing the material circumstances of the act and, if the act involved a depletion of a public-law receivable, paying the amount due. The notification can be filed electronically, among others via ePUAP or the e-Tax Office (e-Urząd Skarbowy). However, voluntary disclosure is ineffective if the authority already had clearly documented knowledge of the act or had begun an activity aimed at uncovering it, unless that activity did not provide grounds for initiating proceedings concerning the act.

A reasonable approach to the first reporting year is therefore as follows: the correction itself should be treated as a way to restore correct reporting and reduce risk, but in the case of materially significant amount errors, a late original submission, a rejected file sent after the deadline, or a file that may be considered defective or unreliable, the need to file a voluntary disclosure must be assessed separately.

Consequences of not submitting a correction

Leaving in the Ministry of Finance system a file whose error the taxpayer knows or should know about may increase evidential, analytical and fiscal penal risk. It does not mean an automatic audit, but it may worsen the taxpayer’s position if the authority later compares JPK_CIT with the books, the CIT-8 or other data.

The evidential consequence should be assessed in light of Art. 193 of the Tax Ordinance Act. Tax books kept reliably and without defects constitute evidence of what they show. The authority does not accept unreliable or defective books as such evidence, unless the defects are not material to the case. JPK_CIT is an electronic representation of the books submitted to the authority, so a material inconsistency between the file and the books, or an incomplete reflection of the books, may trigger a dispute not only about the file itself, but also about the evidential value of the data used for the CIT settlement.

The analytical consequence is that an uncorrected file may remain inconsistent with the CIT-8 return, the financial statements, JPK_VAT files, transfer pricing documentation or other resources of the tax administration. This does not mean automatic initiation of an audit, but it increases the likelihood of a request for explanations or verification activities, in which the authority checks the formal correctness of documents and the consistency of the data presented.

The fiscal penal consequence may arise when the error is material and the taxpayer takes no action despite having identified it. Awareness of the error alone does not determine liability, but the longer the taxpayer leaves a known irregularity unaddressed, the harder it is to demonstrate that the breach was incidental, unintentional or immaterial.

Finally, there is a cascading consequence: if the error in JPK_CIT results from an error in the tax settlement itself, correcting the JPK file alone without correcting the CIT-8 does not remove the tax arrears or the obligation to pay interest. Therefore, once an error is detected, it must be determined not only whether JPK_CIT needs to be corrected, but also whether a parallel correction of the return, payment of arrears or filing of a voluntary disclosure is needed.


How does the ALTOOL JPK CIT application make it easier to manage corrections and verify data?

With the first JPK_CIT, the biggest risk is rarely the click on “send” itself. What matters most is establishing beforehand whether the accounting data is complete, whether the chart of accounts has correct tax tags, whether partial files cover the entire reporting period without gaps or duplicates, and whether the data in JPK_KR_PD is consistent with the CIT-8 and the books. ALTOOL JPK CIT supports precisely this stage of the process.

The tool helps at three stages: when verifying data before submission, when identifying inconsistencies after submission, and when preparing an orderly correction path once an error has occurred. It makes it possible to compare the original file with the correction, generate a report of differences and gather the documentation needed in case of questions from the authority. As a result, the decision to correct has a documented internal justification, rather than being an ad hoc action taken after a problem is detected.

A JPK_CIT correction should not be a hasty reaction, but part of a controlled tax process. In such a process, the quality of source data is checked before an error becomes a topic of discussion with the tax office.


FAQ: frequently asked questions about JPK CIT corrections

Deadline for a JPK CIT correction: by when must it be submitted?

A correction can be submitted after the deadline for the original JPK_CIT submission. There is currently no separate statutory end date for a voluntary JPK_KR_PD correction, but it should not be delayed. The sooner the taxpayer corrects a known error, the easier it is to show that it acted proactively and limited the risk of unreliable or defective reporting. A JPK_CIT correction must also be distinguished from voluntary disclosure: voluntary disclosure may be ineffective if the authority already had clearly documented knowledge of the act or had begun activities aimed at uncovering it.

Can a JPK CIT correction be submitted more than once?

Yes. Ministry of Finance explanations indicate that a correction may relate to the original file or to a previously submitted correction. In practice, this means that further corrections of the same period are possible if additional errors come to light after an earlier correction. Each subsequent correction should cover the full scope of data for the corrected period, not only the difference compared to the previous version.

Must a JPK CIT correction be signed by the same person who signed the original file? How can a correction be signed?

There is no such requirement. What matters is that the correction is signed by a person authorised at the time of submission. JPK_PD can be signed with a Trusted Profile (Profil Zaufany), a qualified electronic signature or, where the taxpayer is an individual, a signature based on authorisation data. From 16 June 2026, the UPL-1 power of attorney to sign returns submitted by electronic means also covers authorisation to sign JPK_PD files. However, UPL-1 should not be referred to as a general power of attorney, because a general power of attorney under the Tax Ordinance Act is a separate instrument.

Does the tax office report errors in JPK CIT before initiating an audit?

There is no guaranteed, automatic warning. After submission, the processing status of the file can be checked and the official confirmation of receipt downloaded, but this primarily confirms technical acceptance of the file, not substantive acceptance of the data. The authority’s doubts may only come to light during verification activities, a request for explanations, a tax audit or a customs and tax audit.

How much time does the authority have to review a JPK CIT correction?

There is no single statutory deadline for the substantive review of a JPK_KR_PD correction. The submission status and the UPO relate to technical acceptance of the file. If the correction becomes part of verification activities, an audit or tax proceedings, the deadlines applicable to that procedure apply, not a separate deadline for the JPK correction itself.

Does a JPK CIT correction affect other proceedings, such as a VAT audit?

There is no automatic effect here. A JPK_CIT correction does not in itself trigger a JPK_VAT correction, nor does it initiate or conclude other proceedings. It may, however, be of analytical or evidential significance if it reveals inconsistencies between the books, revenue, costs, invoices, JPK_VAT or other data available to the authority. The impact on other proceedings always requires a separate assessment.

Must an error be reported if it has not come to light and nobody has noticed it?

If the taxpayer has itself identified an error in a successfully submitted JPK_KR_PD, it should not assume that the authority’s lack of reaction solves the problem. The starting point should be an assessment of whether the error concerns data required for the given year and whether it affects the reliability or defectiveness of the books submitted. If the error concerns formal or amount data in the submitted file, the appropriate response may be a JPK_KR_PD correction. If the information was not mandatory for the given year, for example because it fell within the transitional simplification for counterparty data or the KSeF number, the basis for not submitting a correction should be documented.

Will the rules for JPK CIT corrections change?

Possibly. The draft act numbered UDER111 provides for standardising the rules for correcting electronically submitted tax books and placing these rules in the Tax Ordinance Act. However, this is a draft, not law in force. Until the new provisions are enacted and enter into force, the current regulations and the current Ministry of Finance explanations on JPK_KR_PD must be applied.


Sources

  • Act of 15 February 1992 on corporate income tax, Art. 9(1c), (1d), (1e), (1g) and (1h) and Art. 27(1).
  • Act of 29 August 1997, Tax Ordinance Act, Articles 80a and 80b, Art. 81, Art. 81b, Art. 193, Art. 193a.
  • Act of 10 September 1999, Fiscal Penal Code, Art. 16, Art. 61a.
  • Regulation of the Minister of Finance of 16 August 2024 on additional data to be added to accounting books subject to submission under the Corporate Income Tax Act, Journal of Laws 2024, item 1314.
  • Regulation of the Minister of Finance and Economy of 15 December 2025 amending the regulation on additional data to be added to accounting books subject to submission under the Corporate Income Tax Act, Journal of Laws 2025, item 1828.
  • Regulation of the Minister of Finance and Economy of 16 February 2026 on the extension of deadlines for submitting accounting books in respect of corporate income tax, Journal of Laws 2026, item 188.
  • Act of 15 May 2026 amending the Personal Income Tax Act, the Corporate Income Tax Act and the Act on flat-rate income tax on certain revenue earned by individuals, Journal of Laws 2026, item 779.
  • Draft act amending the Tax Ordinance Act and certain other acts, draft no. UDER111, List of Legislative and Programme Work of the Council of Ministers.
  • Ministry of Finance, “Questions and answers on JPK_PD (JPK_KR_PD and JPK_ST_KR)”, podatki.gov.pl.
  • Ministry of Finance, “JPK_PD: basic information, preparation and submission, signing JPK_PD”, podatki.gov.pl.
  • Ministry of Finance, “Information brochure on the JPK_KR_PD(1) structure”, podatki.gov.pl.


Article updated: September 2026.

JPK CIT audit: how does the tax authority select companies for review in 2026?

JPK CIT: your books under the tax authority’s scrutiny

JPK CIT is the informal name for the new obligations to report books and records in income taxes. For CIT taxpayers, the most important element is the JPK_KR_PD structure, i.e. the electronic form of the accounting books supplemented with tax data.

JPK CIT reporting covers two structures: JPK_KR_PD, relating to the accounting books, and JPK_ST_KR, covering the register of fixed assets and intangible assets. From the perspective of analysing tax settlements and reporting deadlines, JPK_KR_PD is of particular importance. It contains, among other things, data on accounts and accounting entries, counterparties, and differences between the financial result and the tax result. This gives the tax authorities broader opportunities to verify the consistency of settlements and to identify areas requiring clarification.

JPK_KR_PD is not an ordinary data export from an accounting system. It is a file prepared in such a way that the tax administration can process and analyse it automatically. This follows from Art. 193a § 2 of the Tax Ordinance Act, under which the logical structure of electronic tax books and accounting documents must allow for automatic data analysis. In other words, the legislator already provided in the law that JPK is to serve automatic data analysis, not merely act as a digital version of a paper ledger.

The legal basis for the obligation of CIT taxpayers is Art. 9(1c) of the CIT Act. This provision requires taxpayers to keep accounting books using computer software and, after the end of the tax year, to submit them to the competent head of the tax office in a structure compliant with Art. 193a § 2 of the Tax Ordinance Act. For companies without legal personality, the relevant rules follow from Art. 9(1e) of the CIT Act, and for tax capital groups, from Art. 9(1g) of the CIT Act.

The JPK_KR_PD obligation is being introduced in stages. In 2026, JPK_KR_PD was submitted by the largest CIT taxpayers and tax capital groups. The full schedule, thresholds and deadlines are described in our article JPK_CIT in 2026: deadlines, JPK_KR_PD structure and new obligations. In this context, the key point is that the tax authority is starting to receive accounting data in a format suitable for automatic processing and comparison.

The scope of data in JPK_KR_PD is broader than the accounting entry itself. The Regulation of the Minister of Finance of 16 August 2024 requires the books to be supplemented with, among other things, counterparty data, account tags based on the dictionaries of the Ministry of Finance (MF), and the data needed to reconcile the accounting result with the tax base. The structure also includes field D_12, i.e. the number identifying an invoice or corrective invoice in KSeF. However, it does not apply to every invoice. Field D_12 is required for transactions documented with an invoice or corrective invoice issued via KSeF by the entity submitting the JPK.

In practice, this means that JPK_KR_PD makes it possible to look beyond the bookkeeping entries themselves. It also allows analysis of how the taxpayer classifies revenue, costs, and the differences between the accounting result and the tax result.


What does the Ministry of Finance do with JPK CIT files? Automated audits

There is no official description of an algorithm showing how MF or the National Revenue Administration (KAS) analyses JPK_KR_PD and selects companies for audit on that basis. There are, however, official communications confirming that the tax administration uses risk analysis, analytical tools, Big Data and statistical models, particularly in VAT.

This is an important distinction. It is fair to say that JPK_KR_PD gives the tax authority material for analysis. However, it cannot be claimed that we know a specific JPK CIT audit algorithm, because no such mechanism has been publicly described.

The safest way to look at this topic is in three steps.

  • First, the law expressly assumes automatic analysis of JPK data (Art. 193a § 2 of the Tax Ordinance Act). Moreover, the explanatory memorandum to the introduction of JPK CIT reporting expressly states that the aim of the changes was “to enable the tax administration to verify the correctness of settlements and detect abuse remotely, without the need to carry out on-site activities, and to increase their effectiveness.”
  • Second, KAS publicly states that it uses analytics, Big Data and risk analysis to direct verification activities. The KAS Analysis Department is responsible, among other things, for risk analysis in the tax administration’s area of activity.
  • Third, a practical conclusion can be drawn from these two facts: data from JPK_KR_PD may be used to select taxpayers for verification activities or audits. This still does not mean, however, that MF has disclosed a specific list of rules, alerts or risk scoring for JPK CIT.

Most of the official information available today concerns not JPK CIT but earlier experience with JPK_VAT and STIR. MF reported using JPK_VAT for automated verification activities, and KAS described the so-called Analytics Engine (Silnik Analiz), which in the VAT area used statistical and econometric modelling and machine learning. This is a good point of reference, but not proof that the same mechanism is already in place for JPK CIT.


Cross-checking data: JPK CIT vs JPK_VAT

There is no public confirmation that MF applies a specific, named mechanism for cross-checking JPK_KR_PD against JPK_VAT. Such data comparison is, however, technically possible, because both data sets reach the tax administration and concern, among other things, transactions, counterparties, documents and settlement periods.

In VAT, the use of JPK for analysis is already described in public materials from the Supreme Audit Office (NIK) and MF. NIK pointed out that JPK enabled broad analysis of data on counterparties and transactions, and that the administration developed reports comparing the JPK_VAT of a taxpayer with that of its counterparties. MF also stressed that JPK_VAT contains the data needed to analyse the correctness of VAT settlements, and that VAT settlements are automatically verified for the correctness of output and input tax.

For JPK CIT, however, caution is needed. It is true that the tax authority, thanks in part to tools such as ARANEA, most likely has the technical capability to compare data from different structures. Nevertheless, at least for now, there is no publicly known algorithm that automatically matches specific JPK_KR_PD fields with specific JPK_VAT fields.

It is also necessary to distinguish between markings specific to different structures. The MPP or TP markings are elements of JPK_VAT/JPK_V7 and relate to procedures or transaction types. In JPK_KR_PD, other elements are relevant: the Kontrahent (counterparty) node, the chart of accounts, the Dziennik (journal of entries) and account tags, including S_12_1, S_12_2 and S_12_3 in the ZOiS node, i.e. the trial balance.

It is worth noting that parliamentary question no. 9710 of 2025 concerned automatic analysis and algorithms in JPK_VAT. This shows that the automation of JPK is also present in public debate. It is not, however, a source confirming a specific mechanism for selecting JPK CIT audits.


Deviations in financial ratios and warning algorithms

MF has not published a list of warning indicators for JPK CIT. Therefore, any examples of such indicators must be described as possible areas of risk analysis, not as known rules of how the system works.

In practice, such areas may include, among others, consistency of the accounting result with the tax base, the level of costs permanently not constituting tax-deductible costs, exempt and non-taxable revenue in the current year, balances of settlements with related parties, recurring losses despite high revenue, or unusual relationships between the books and the CIT-8 return.

These are areas that naturally follow from the content of JPK_KR_PD and the logic of risk analysis. They should not, however, be presented as an official MF checklist. The safe thesis is simpler: the more structured data reaches the tax authority, the easier it is to spot unusual relationships, discrepancies and points requiring clarification.


Which account tagging errors might the MF system respond to?

The key is to distinguish between technical and substantive errors. Technical errors may be detected as early as file validation. Substantive errors may create an analytical risk, but assessing them requires examining the accounting entries, the accounting policy and the actual nature of the transactions.

It would be overly optimistic to claim that “an automated system will never detect a substantive error”. Analytical tools can point to inconsistencies, deviations or unusual data. An automated system does not, however, decide on its own whether a given account has been correctly assigned to a tax tag. That requires an assessment of documents, accounting principles and the way the company operates.

The JPK_KR_PD structure includes, among others, the Naglowek, Podmiot1, Kontrahent, ZOiS, Dziennik, Ctrl and RPD nodes. The header contains the CelZlozenia field, where the value “1” means the first submission and “2” a correction. In 2026, reference should be made to the JPK_KR_PD(1) structure and the current v1-1 schema published by MF. The update to version v1-1 resulted from aligning the dictionaries with the Regulation of the Minister of Finance of 16 August 2024.

Technical errors include, for example, non-compliance with the XSD schema, a missing required field, an incorrect data type, an incorrect date format, an invalid dictionary value, exceeding the character limit or inconsistent control data. Such an error may result in the file being rejected, no UPO (official confirmation of receipt) being issued, or the need for a technical correction.

Substantive errors are more difficult. A file may be technically correct but still contain an incorrect tax classification. For example, an account may be assigned to the wrong tag, a cost may be incorrectly treated as tax-deductible, and the difference between the accounting and tax results may be recognised incorrectly. In the JPK_KR_PD FAQ, MF indicates that, given the different accounting policies and different methods of record-keeping, it is not possible to create a single universal instruction for completing fields S_12_1 to S_12_3. The taxpayer must therefore independently analyse the accounting entries and the actual nature of the business events.

The “optional” status of fields is also important. The fact that a field may be technically optional does not mean it is left to discretion. MF indicates that fields S_12_1, S_12_2 and S_12_3 may remain empty only in specific cases, e.g. under special exemptions for entities applying IFRS. As a rule, the taxpayer should apply the appropriate tag if this follows from the content of the books and the nature of the account.

The safe conclusion is as follows: the system may stop the file or flag technical problems, and data from a correctly submitted JPK_KR_PD may later be subject to risk analysis. An error in the file does not in itself mean an automatic penalty, however. A sanction requires a separate legal basis, the appropriate procedure and a determination of who is responsible for the infringement.


From prevention to targeted audits: how to prepare your team for questions from the tax office

Data from JPK_KR_PD may lead to various responses from the authority: from verification activities, through a tax audit, to a customs and tax audit in more serious cases. Which procedure is chosen depends on the type of irregularity and the authority’s risk assessment.

Verification activities are the least formalised. As part of them, the authority may check, among other things, whether returns have been filed and tax paid on time, the formal correctness of documents, and whether the data is consistent with the documents submitted.

In practice, this may mean a request for explanations, a request for a correction, or an attempt to reconcile the data with the CIT-8 return.

A tax audit is a formal procedure provided for in the Tax Ordinance Act. Its purpose is to check whether the taxpayer is fulfilling its tax obligations. As a rule, the authority gives prior notice of its intention to initiate an audit, but the law provides for exceptions to this rule. JPK_KR_PD may shorten the audit preparation stage, because some of the data the authority used to obtain only in the course of proceedings is now received after the end of the year.

A customs and tax audit is a separate procedure governed by the KAS Act. It covers, among other things, checking compliance with tax law. KAS states publicly that audit activities are directed where risk analysis shows a higher probability of irregularities.

It is too early to assess the effects of using JPK_KR_PD in tax audits. The first reporting cycle ended on 31 July 2026, and publicly available KAS data do not make it possible to isolate audits in which this file was used. Experience with JPK_VAT may show the analytical potential of reporting, but it does not yet prove the effectiveness of JPK CIT.

Before submission, it is worth checking the consistency of the data in JPK_KR_PD with the tax calculation and the CIT-8 return, explaining any discrepancies and verifying the substantive correctness of the file. It is also worth organising the documentation that makes it possible to reconstruct how aggregated amounts were determined. As a result, if the tax office asks about specific items, it will be easier to quickly prepare consistent and well-documented explanations.


Check your JPK CIT before the tax office does

Before JPK_KR_PD reaches the tax office, it is worth reviewing it the way a tax department would during an internal audit: technically, from a tax perspective and in terms of process.

ALTO supports clients with the ALTOOL JPK CIT tool, available in SaaS and on-premise versions. The application helps automate key stages of reporting: from data retrieval, through validation, to generating reports that comply with current requirements. It also enables mapping of financial data, adding data from outside the accounting system, and separately adding accounting and tax tags to accounts. This is particularly important for companies working on complex or inflexible ERP systems.

ALTO also offers comprehensive implementation support, including analysis of CIT settlement processes, analysis of data completeness and identification of areas requiring adjustment in order to assign the appropriate tags.


FAQ: Frequently asked questions about JPK CIT audits


Does the tax authority automatically detect errors in JPK CIT?

At the submission and validation stage, mainly technical errors are detected, e.g. non-compliance with the XML schema or missing required data. Substantive errors may attract the attention of analytical systems, but assessing them requires an analysis of the taxpayer’s books, documents and accounting principles.


Is JPK CIT cross-checked against JPK_VAT?

There is no official confirmation of a specific mechanism for cross-checking JPK_KR_PD against JPK_VAT. Such a comparison is technically possible, but it should not be presented as a disclosed MF algorithm.


Is there a public list of indicators that MF checks in JPK CIT?

No. MF has not published a list of alerts for JPK CIT. Areas relevant to risk analysis can be identified, but not as an official tax authority checklist.


What are the consequences of an error in a JPK CIT file?

Sanctions under the Fiscal Penal Code depend on the type of error, its tax consequences and to whom liability can be attributed.


Sources

  1. Art. 193a § 2 of the Tax Ordinance Act.
  2. Art. 9(1c), (1e) and (1g) of the CIT Act.
  3. Regulation of the Minister of Finance of 16 August 2024 on additional data to be added to accounting books subject to submission under the Corporate Income Tax Act, Journal of Laws 2024, item 1314.
  4. MF/KAS web pages “JPK_PD” and “JPK structures in income taxes”.
  5. JPK_KR_PD(1) information brochure, JPK_KR_PD(1) v1-1 schema and MF FAQ on JPK_PD.
  6. KAS communications on risk analysis, Big Data, JPK_VAT, STIR and the Analytics Engine.
  7. Parliamentary question no. 9710/2025 on JPK_VAT verification procedures.
  8. ALTO materials on ALTOOL JPK CIT and comprehensive preparation for JPK CIT.

Article updated: September 2026.
ALTO named Poland Transfer Pricing Advisory Firm of the Year at the ITR Europe Tax Awards

ALTO has won an ITR Europe Tax Award for the first time in its history. In the Transfer Pricing category we received the title of Poland Transfer Pricing Advisory Firm of the Year, awarded to the highest rated transfer pricing advisory firm in Poland in this year’s edition.


itr tax awards poland 2026 ALTO TP firm of the year


Recognition for the Transfer Pricing team

This result is the work of the entire ALTO Transfer Pricing team, led by Aneta Grzyb. It reflects a series of projects carried out for clients in 2025/2026 and submitted for the ranking.

The ITR Europe Tax Awards are among the most recognisable distinctions in the European tax industry. They go to firms and advisors who set quality standards and bring new solutions to the market. That makes joining this group all the more satisfying for us.

Transfer pricing is an area where an off the shelf solution is rarely enough. Every project starts with a conversation about how the client’s business actually works, where value is created and which risks are real rather than purely theoretical. Only then can we build documentation or a policy that will still hold up several years from now.

This title belongs first of all to the team, which works this way consistently, including on the most demanding projects. I would also like to thank our clients. They bring us into difficult and non standard matters, share their business context and treat transfer pricing as part of their strategy rather than a box to tick. Without that kind of partnership there would be neither these projects nor this award.

-comments Aneta Grzyb, Partner and Leader of the Transfer Pricing Practice at ALTO


What is taken into account in the assessment?

The ITR panel assesses submissions broadly. The criteria include:

  • the experience of the experts,
  • the scale of the firm’s operations,
  • the complexity of the projects delivered,
  • the innovation behind the solutions applied,
  • market impact,
  • feedback from clients and other professionals in the industry,
  • the development of the organisation.

The result therefore does not rest on a single project or on the size of the team alone. It is an assessment of how we work day to day and how that work is received by the market. This is what makes it particularly valuable to us.


More results still to come

We are still waiting for further results of this year’s ITR rankings, both firm and individual. We will share each of them on our website and across our social media channels.

B2B audits are gaining momentum. The National Labour Inspectorate (PIP) is publishing its first interpretations.

Abbreviations used in this article

PIP – the National Labour Inspectorate.

GIP – the Chief Labour Inspector.

ZUS – the Social Insurance Institution.

KAS – the National Revenue Administration.

B2B – business-to-business, here: cooperation with a self-employed contractor instead of an employment contract.

Since August we have been observing heightened inspection activity by the National Labour Inspectorate in the area of B2B cooperation models. In parallel, inspection activities are being carried out across the country by ZUS and the tax authorities, aimed at verifying relationships based on B2B and civil law contracts.

The key question today is not whether the B2B model is permissible, but whether it will be able to withstand an inspection by PIP, ZUS or the tax authorities.

In response to these challenges, a new safeguarding tool has appeared. The National Labour Inspectorate has begun issuing individual interpretations.


An overview of the first PIP interpretations

Date Industry Outcome 3 key factors
28.07.2026 Sales / marketing / business development Favourable – no employment relationship
  • freedom as to the place and time of performing the services
  • absence of ongoing instructions and supervision
  • possibility of substitution and a focus on the commercial result
29.07.2026 IT industry / software development Favourable – no employment relationship
  • possibility of refusing to accept assignments
  • absence of subordination as to the manner, place and time of work
  • contractual liability and the possibility of providing services to other entities
29.07.2026 IT industry / Project Manager Favourable – no employment relationship
  • absence of employer powers over the team
  • independent organisation of project work
  • responsibility for the project result and contractual risk
03.08.2026 Temporary work agency (warehouse, shop and production work) Unfavourable – in fact a temporary employment relationship
  • obligation to perform work at the place and time indicated by the client
  • the simple nature of the work and subordination to ongoing instructions
  • illusory substitution not excluding personal performance of the work
05.08.2026 Temporary work agency (analogous model) Unfavourable – in fact a temporary employment relationship
  • direction by the user client
  • work at a specified place and time
  • economic risk on the agency’s side
03.08.2026 Transport of children with disabilities – driver Unfavourable – employment relationship
  • performance of work throughout the school year
  • use of the vehicle and organisation provided by the entity
  • absence of economic risk on the provider’s side
05.08.2026 Transport of children with disabilities – carer Unfavourable – employment relationship
  • obligation to perform the work personally
  • fixed place and time of performing the duties
  • integration into the organisational structure of the entity providing the public service
17.08.2026 Retail and bakery production (students) Unfavourable – employment relationship despite flexible hours
  • ongoing tasks assigned by the employer
  • participation in the core sales and production process
  • the absence of autonomy in determining how the entrusted activities are carried out is more significant than freedom to choose when the tasks are performed


Key conclusions from the interpretations issued so far

The first decisions show a very clear interpretative trend on PIP’s part, consistent with the inspectorate’s earlier announcements:

The greatest chances of withstanding scrutiny are enjoyed by B2B models based on:

  • the provider’s autonomy,
  • responsibility for the result,
  • the ability to organise one’s own work
  • and the bearing of genuine economic risk

(often found, for example, in IT and professional services).


The greatest risk of challenge arises where the provider:

  • carries out tasks according to superiors’ directions,
  • works at a specified place and time
  • and does not bear the economic risk of the activity

(often found, for example, where simple, routine work is entrusted).


What a PIP individual interpretation is and why to use it

An individual interpretation is a written assessment by the Chief Labour Inspector as to whether the legal relationship described in the application constitutes an employment relationship within the meaning of Article 22 § 1 of the Labour Code. The institution is introduced by Article 14b of the Act on the National Labour Inspectorate, and applications may be submitted from 8 July 2026.
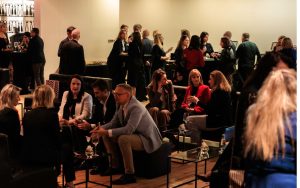
An application may concern both a model already operating within the company and a future event, that is a structure that is only being planned. This is significant for organisations preparing to remodel their cooperation with contractors and wishing to know the authority’s position before implementing changes.

Only the entity entrusting the work may apply for an interpretation, as indicated in Article 13(1) to (6) of the Act on the National Labour Inspectorate: an employer, an entrepreneur or another organisational unit for which the work is or was performed. A person cooperating under a B2B model has no standing to submit an application in their own case.

The issuance of an interpretation is subject to a fee of PLN 40 for each separate set of facts or future event presented in the application. An interpretation is issued without undue delay, no later than within 30 days of receipt of a complete application. If the application has formal deficiencies or proof of payment has not been attached, the applicant has 7 days to supplement it, and once that deadline has passed without effect the application is left unexamined.

The commercial rationale for this tool follows from how the inspectorate’s powers have changed. From 8 July 2026, a district labour inspector may establish the existence of an employment relationship by administrative decision, without a prior court ruling. The burden of procedural initiative has therefore shifted to the entrepreneur. An individual interpretation works in the opposite direction: it makes it possible to obtain the authority’s position earlier, under controlled conditions, instead of learning it only in the course of an inspection.

An interpretation is not binding on the applicant, who is not obliged to follow it. It is, however, binding on the authorities of the National Labour Inspectorate. An entity that has followed the interpretation it received cannot be subjected to sanctions within the scope covered by the decision.


What a PIP interpretation does not resolve

The protection under Article 14b operates within the limits of the National Labour Inspectorate’s powers and solely in relation to the set of facts described in the application. An interpretation does not close off contribution or tax risk and does not exclude the possibility of an inspection being carried out.

Below are the limitations that in practice determine whether an application makes sense in a specific organisation.

  • An interpretation does not block an inspection. PIP retains the right to examine the actual nature of the cooperation.
  • The protection falls away where the facts diverge. If the inspector establishes that practice departs from the description contained in the application, the interpretation ceases to protect. A model described more favourably than it actually looks not only fails to provide protection, but itself becomes material in the case.
  • An interpretation is not binding on ZUS or the National Revenue Administration. Both authorities conduct their own proceedings under their own provisions. Outstanding contributions are not a sanction but a liability, so protection against sanctions does not cover them.
  • An issued interpretation is forwarded to ZUS and KAS. A company should take into account that its position and the description of its model reach authorities that may conduct separate proceedings.
  • It does not cover matters already under way. The Chief Labour Inspector will not issue an interpretation on elements that, as at the date the application is submitted, are the subject of PIP or ZUS proceedings. Once an inspection has begun, it is too late to ask.
  • It does not replace a review of operational practice. An application describes a model. If the day-to-day organisation of work departs from that description, the value of the interpretation is illusory. The order should be the reverse: first a review of the documentation and the realities of the cooperation, then the application.


Frequently asked questions (FAQ)


Who may submit an application for a PIP individual interpretation?

Only the entity entrusting the work, listed in Article 13(1) to (6) of the Act on the National Labour Inspectorate. A person providing services under a B2B model or a mandate contract may not submit an application in their own case.


How much does an application for an interpretation to the Chief Labour Inspector cost?

PLN 40. If the application covers more than one separate set of facts or future event, the fee is payable for each of them.


How long does one wait for an interpretation?

Without undue delay, no later than 30 days from the date of receipt of a complete application together with proof of payment.


Does a PIP interpretation protect against ZUS and the tax office?

Not automatically. An interpretation is binding on PIP authorities. ZUS and KAS conduct their own proceedings and are not bound by the Chief Labour Inspector’s position, but an issued interpretation is forwarded to them.


Can an unfavourable interpretation be appealed against?

An interpretation is issued in the form of a decision against which a means of appeal to the court is available, on the terms set out in the Code of Civil Procedure. The decision contains instructions on how and by when it is to be lodged.


Are the interpretations issued published?

Yes, after the removal of data identifying the applicant and other entities indicated in their content. This means that subsequent decisions will gradually build up a picture of PIP’s interpretative line, including for companies that have not themselves submitted an application.
Is a PIP interpretation the right solution for your company? Would you like to check whether the B2B model operating in your organisation is resilient to inspection by PIP, ZUS and the tax authorities? Get in touch with us!


National Labour Inspectorate (PIP) audit of B2B contracts: How to prepare your organization and navigate the process without operational paralysis?

Abbreviations used in this article

PIP – the National Labour Inspectorate.

ZUS – the Social Insurance Institution.

KAS – the National Revenue Administration.

B2B – business-to-business, here: cooperation with a self-employed contractor instead of an employment contract.


An inspection by the National Labour Inspectorate concerning the way cooperation is carried out under a B2B model is not solely an HR issue. The inspector analyses the actual manner in which the work or services are performed and the circumstances of the cooperation, which in practice involves the management board, the legal department, HR, finance and operational managers all at once. The greatest threat is not the inspector’s presence at the company as such, but the organisational chaos that arises when each unit answers questions on its own and without coordination.

Bearing in mind that the new provisions granting labour inspectors the power to issue decisions establishing the existence of an employment relationship have applied in practice since July 2026, it must be assumed that inspection practice is only taking shape. As at the date of publication, there is no settled line of case law relating to labour inspectors’ new powers. The amendment did not de facto change the rules for conducting inspection activities (that is, the way evidence is gathered, witnesses are questioned, etc.), but above all broadened the catalogue of possible decisions concluding the proceedings – what changed were the effects of the inspector’s findings and their powers once the inspection is complete. This article therefore treats a PIP inspection not as a one-off “visit from an official”, but as a risk management project that may initiate a sequence of actions involving ZUS and the National Revenue Administration as well.


National Labour Inspectorate inspections in 2026 – what did the new PIP B2B reform change?

The PIP reform did not create a new type of inspection – it changed how an inspection may end. The National Labour Inspectorate was already previously entitled to inspect the way work is performed and compliance with labour law provisions, including where the cooperation was carried out on the basis of civil law contracts or in the form of business activity. What is new is that such an inspection may now lead to the commencement of administrative proceedings concluded by a decision establishing the existence of an employment relationship, on the basis of Article 11 of the Act on the National Labour Inspectorate in the wording established by the Act of 11 March 2026 (Journal of Laws of 2026, item 473).

Until now, if an inspector concluded that the cooperation infringed labour law standards, they could issue representations, issue orders within the scope of their statutory powers and – above all – bring an action before the court to establish the existence of an employment relationship, or join proceedings already under way. An inspection is now no longer merely an information-gathering stage – it may become the beginning of a multi-stage process involving ZUS and KAS as well.

It is worth emphasising that a PIP B2B inspection may be commenced both as a result of a complaint by a cooperating person and on the initiative of the National Labour Inspectorate, including as part of inspection plans and on the basis of information obtained by the inspectorate (including from sources such as data provided by ZUS or the tax office). An entrepreneur should therefore not assume that the absence of a conflict with a contractor eliminates the risk of an inspection.


Preparing for a PIP inspection – who within the company’s structures is responsible for dialogue with the inspector?

Good organisational practice is to designate one person to coordinate contact with the authority – it is a mistake to assume that responsibility for the inspection rests solely with HR. In the case of inspections of B2B models, each department holds a different fragment of the information, and a lack of coordination very easily leads to contradictory explanations being provided.

The coordinating person need not be a member of the management board, but should have appropriate authority and the ability to contact the individual departments quickly. The role of the individual organisational units usually looks as follows:

  • HR is responsible for the documentation concerning the cooperation, internal policies and contact with the persons performing the services.
  • The legal department analyses the legal basis for the inspection activities and the scope of the entrepreneur’s obligations arising from the Act on the National Labour Inspectorate, and also prepares the entrepreneur’s positions.
  • The finance / accounting department assesses the financial risks arising from the inspection and keeps in mind the potential impact of the PIP inspection on tax and contribution obligations and risks.
  • The management board takes strategic decisions and approves the manner in which dialogue with the authority is conducted.
  • Operational managers are often the most important source of information about the actual manner in which the cooperation is carried out – their explanations may be of material significance in establishing how the cooperation was in fact performed.

All participants in the inspection should be familiar with a common communication strategy. This is not about obstructing the inspection, but about ensuring consistency in the information provided.


The inspection procedure step by step – how to safeguard daily business?

A well-prepared organisation is able to go through a PIP inspection and at the same time carry on projects as normal, provided that individual responsibilities have been defined in advance. The successive stages of the procedure are set out below:

  • Formally receive the inspector and verify their authorisation and the scope of the inspection before handing over any documents.
  • Designate a person responsible for ongoing contact with the authority and for keeping a register of all documents provided.
  • Make copies of all documentation provided to the inspector and document the course of the inspection – this later makes it possible to reconstruct the evidence and prepare any objections to the inspection report.
  • Limit the number of people in direct contact with the inspector – the more employees who provide explanations on their own, the greater the risk of inconsistency.
  • Do not subordinate current operations entirely to the inspection – if individual responsibilities are defined in advance, the company can carry on projects as normal while the inspection is under way.

It is very good practice to appoint and work with a professional representative (a legal counsel, an advocate or a tax adviser) specialising in representing entrepreneurs during inspections. They will help develop the best strategy for conduct during the inspection and enforce it throughout the case. Thanks to their professional experience, an external representative is usually able to assess “which way” the inspection activities are heading and to advise which documents and explanations should be submitted.


Which documents may an inspector demand, and what goes beyond their powers in a PIP B2B inspection?

An inspector may demand documents relevant to establishing whether the cooperation was carried out in conditions characteristic of an employment relationship, on the basis of the inspection powers set out in Article 23 of the Act on the National Labour Inspectorate. In practice this concerns above all:

  • B2B contracts and their amendments,
  • invoices and cooperation schedules,
  • project documentation,
  • internal rules applicable to providers,
  • business correspondence,
  • documents showing how the work is organised.

This does not, however, mean that the authority may demand any documents whatsoever in the entrepreneur’s possession – the scope of the request should remain connected with the subject matter of the inspection being conducted. The entrepreneur is obliged to enable the inspection to be carried out, but at the same time has the right to expect that all activities will be performed within the limits of the inspector’s statutory powers, including the limits arising from the provisions of Chapter 5 of the Entrepreneurs’ Law, which governs restrictions on inspections of business activity.

It is also worth bearing in mind business secrets. The mere fact that a document is covered by business secrecy does not preclude the possibility of showing it to the inspector, but the entrepreneur should mark such documents appropriately and control the scope of the information provided.


The post-inspection report and what next? When the case lands on another institution’s desk

Signing the post-inspection report is not the end of the matter – from the perspective of legal and tax risk it may, unfortunately, be only the beginning. Once the inspection activities have been concluded, the inspected entity has the right to raise substantiated objections to the findings contained in the report.

This is an extremely important stage, because it is precisely then that the inspector’s findings of fact can be challenged, overlooked evidence pointed out, or an incorrect assessment of the material gathered highlighted. Disregarding this opportunity may make it more difficult to defend one’s position in subsequent proceedings.

If the inspection findings point to the existence of an employment relationship, the matter may move to the administrative stage conducted by PIP. In parallel or subsequently, an interest in the case may also be shown by ZUS – as regards coverage by social insurance and the amount of contributions, which we discuss in more detail in the article on [appealing against a ZUS decision following the reclassification of a B2B contract] – and, depending on the circumstances, by the National Revenue Administration authorities (the tax office or the customs and fiscal office).

From the management board’s perspective, the most important mistake is passively waiting to see how events unfold. A far better solution is to carry out an internal audit of all B2B cooperation models before the whole process has been concluded – we describe it in the article on [an urgent remedial audit of B2B models]. This makes it possible not only to prepare arguments in the specific case, but also to identify similar risks in the remaining relationships with contractors and to reduce the likelihood of further inspections or disputes with other authorities.


Frequently asked questions


Is a PIP inspection of B2B contracts a new type of inspection introduced by the reform?

No. PIP was able to inspect the way civil law contracts were performed previously as well. The reform changed above all how such an inspection may end – it may now lead to an administrative decision establishing the existence of an employment relationship.


Is the HR department alone responsible for a PIP inspection at a company?

It should not be. With inspections of B2B models, an inspection very quickly involves the management board, the legal department, HR, finance and operational managers. It is recommended that one person be designated to coordinate the entire process. It is also worth using the services of a professional representative (a legal counsel, an advocate, a tax adviser).


Which documents may a PIP inspector demand in an inspection of B2B contracts?

Documents relevant to establishing whether the cooperation was carried out in conditions characteristic of an employment relationship – in particular B2B contracts, invoices, cooperation schedules, project documentation and business correspondence. The scope of the request must remain connected with the subject matter of the inspection.


May a PIP inspection be commenced without a prior conflict with a contractor?

Yes. An inspection may be commenced both as a result of a complaint by a cooperating person and on the initiative of the National Labour Inspectorate, including as part of inspection plans and on the basis of information obtained by the inspectorate.


Sources

  • Act of 13 April 2007 on the National Labour Inspectorate, consolidated text (Journal of Laws of 2024, item 1712), Articles 11, 23 and 31
  • Act of 11 March 2026 amending the Act on the National Labour Inspectorate and certain other acts (Journal of Laws of 2026, item 473)
  • Act of 17 November 1964 – Code of Civil Procedure, consolidated text (Journal of Laws of 2026, item 468), Article 63(1)
  • Act of 6 March 2018 – Entrepreneurs’ Law, consolidated text (Journal of Laws of 2025, item 1480), Chapter 5
  • Ministry of Family, Labour and Social Policy, “Reform of the National Labour Inspectorate”

B2B Audits: New Rules, Risks, and Practical Tips for Companies

The new B2B inspection rules require greater operational discipline from companies. Below you will find how an inspection works in practice, what the risks are and how to safeguard your cooperation model.

Polish abbreviations used in this article

PIP – Państwowa Inspekcja Pracy, the National Labour Inspectorate.

ZUS – Zakład Ubezpieczeń Społecznych, the Social Insurance Institution.

KAS – the National Revenue Administration.

BHP – occupational health and safety.


B2B inspections after 8 July 2026: how PIP assesses actual cooperation and which elements most often lead to reclassification?

After 8 July 2026, inspections of B2B cooperation entered an entirely new phase. The National Labour Inspectorate gained tools allowing it to assess more quickly and more effectively whether a relationship with a contractor is genuinely business in nature or displays the features of employment. In practice this means moving away from analysing the wording of the contract alone towards examining the actual manner in which the services are performed, and therefore the level of independence, the organisation of work and the way instructions are given.

For companies using B2B, this is the moment at which putting processes in order and verifying risk becomes necessary. PIP’s new powers, including the ability to issue an administrative decision on the existence of an employment relationship, mean that the cooperation model must be not only well described, but also consistent with day-to-day operational practice.


What changed after 8 July 2026? Key facts for management boards and HR

After 8 July 2026, companies using the B2B model must operate under entirely new supervisory conditions. The reform of the National Labour Inspectorate not only broadened the scope of inspections, but above all changed the way cooperation with contractors is assessed. This means that the risks associated with B2B are more tangible today, and the responses of the supervisory authorities faster and more effective than ever before.


An administrative decision on the existence of an employment relationship

From 8 July 2026, a district labour inspector may independently establish that B2B cooperation displays the features of an employment relationship. An administrative decision replaces lengthy court proceedings, which significantly shortens the response time and increases the risk of immediate financial consequences. This is a fundamental change, because for the first time an inspection authority may directly determine the nature of the engagement.


PIP’s two-stage mode of operation

The new provisions introduced a procedure in which the inspector first issues an order to remedy infringements, indicating the elements of the cooperation requiring correction. Only a failure to respond on the company’s part opens the way to an administrative decision being issued. This model is preventive in nature, but it requires organisations to put processes and documentation in order quickly.


Remote inspections and electronic document flow

PIP may conduct inspections entirely remotely: analysing documents online, questioning the parties by videoconference and issuing electronic inspection reports. This increases inspectors’ availability and allows more frequent inspections, especially in companies operating in a hybrid or distributed model.


Joint risk analysis: PIP, ZUS and KAS

Following the reform, state institutions exchange data on employment, contributions and cooperation models. As a result, companies are selected for inspection on the basis of risk analysis rather than solely on the basis of reports. Consequently, organisations with a large number of contractors or with repetitive settlement patterns may appear more frequently on the list of entities to be verified.


A 12-month adjustment period (until 8 July 2027)

The provisions envisage a one-year period in which companies may put their B2B cooperation model in order without the risk of financial sanctions. Inspections still take place, but their purpose is to identify irregularities and allow them to be remedied. This is the time for a process audit, for standardising documentation and for making sure that the way services are performed is consistent with the wording of the contracts.


How does PIP assess B2B cooperation? Practice counts, not the contract

After 8 July 2026, the National Labour Inspectorate assesses B2B cooperation primarily through the lens of the actual manner in which the services are performed, rather than the wording of the contract. This means that even a correctly drafted contract does not protect the company if day-to-day practice resembles an employment relationship. Inspectors analyse the facts, including the organisation of work, the way instructions are given, the level of the contractor’s independence and the nature of the remuneration, and then compare them with the criteria arising from Article 22 of the Labour Code.


Subordination and the way work is managed

One of the key elements of the assessment is whether the contractor acts independently or is subject to the company’s ongoing direction. Inspectors pay attention to who decides how tasks are performed, who sets priorities, who monitors progress, and whether the contractor can organise their own work independently. If the process resembles typical employee supervision, this is a strong risk signal.


Time and place of performance of the services

PIP analyses whether the contractor is free to choose their working hours and place of work, or whether they operate within a fixed schedule imposed by the company. Fixed hours, mandatory presence in the office or an obligation to report attendance may indicate features of employment. What is crucial is whether the contractor actually enjoys independence, and not merely whether it is written into the contract.


Personal performance of the services and the possibility of substitution

Inspectors examine whether the contractor may entrust the performance of tasks to another person, which is a natural element of business activity. If the cooperation is based on mandatory, personal performance of the services and the company does not allow substitutes, the relationship may be assessed as one of employment. PIP focuses on practice, not merely on the wording of the contract.


The nature of the remuneration and economic risk

In a B2B model the provider should bear economic risk, and their remuneration should reflect the nature of the services. Fixed, lump-sum rates paid regardless of the results of the work, an absence of costs on the contractor’s side or a lack of responsibility for the result may indicate that the self-employment is a sham. Inspectors also analyse whether the contractor provides services to other entities or is in fact tied to a single company only.


Integration with the team and access to benefits

PIP also assesses the degree to which the contractor is integrated into the organisational structures, including participation in team meetings, use of employee benefits, involvement in HR processes and onboarding. The more the cooperation resembles the standard functioning of an employee within the company, the greater the risk of the B2B model being challenged.


Consistency between documentation and operational practice

Inspectors compare the wording of the contract with the actual manner in which the services are performed. If the documentation indicates independence but practice indicates subordination, PIP treats the actual state of affairs as decisive. This means that companies must take care not only over the content of their contracts, but also over the consistency of their operational processes with the B2B model.


What does a B2B inspection look like in practice?

Inspections of B2B cooperation after 8 July 2026 are more dynamic, faster and based on an analysis of the actual conditions in which the services are performed. PIP inspectors use both traditional tools and new remote mechanisms, and their work is supported by data from ZUS and KAS. In practice this means that an inspection may begin unexpectedly, take several forms and cover both documents and the day-to-day organisation of work.


Forms of inspection: on-site, remote and hybrid

An inspection may take place at the company’s premises, entirely online or in a mixed model. In the case of remote inspections, inspectors use videoconferencing, electronic document flow and screen sharing, which allows them to analyse materials in real time. This mode is particularly common in companies operating in a hybrid or distributed model.


The scope of documents and information PIP may demand

An inspector has the right to demand:

  • B2B contracts and amendments,
  • work schedules, reports and timesheets,
  • project documentation,
  • correspondence concerning the manner in which tasks are performed,
  • internal rules, procedures and instructions in force at the company,
  • information on remuneration and the manner of settlement,
  • data concerning the contractor’s other clients (where available).

PIP analyses not only formal documents, but also operational materials that show what the cooperation looks like from day to day.


Interviews with contractors and employees

Inspectors conduct interviews with the people involved in the cooperation, both contractors and the managers supervising their work. The questions concern, among other things, the way instructions are given, the organisation of working time, the scope of responsibility, the possibility of substitution and the level of independence. This is one of the key elements of an inspection, because it makes it possible to establish the actual nature of the relationship.


Analysis of operational practice

PIP compares the wording of the contract with the actual manner in which the services are performed. If the documentation indicates independence but practice indicates subordination, the inspector treats the actual state of affairs as decisive. The matters analysed include:

  • the way tasks are delegated,
  • the contractor’s participation in team meetings,
  • access to tools and systems,
  • use of benefits,
  • the obligation to report work results.

It is precisely this part of the inspection that most often determines how the cooperation is assessed.


An order to remedy infringements

If the inspector finds irregularities, they may issue an order to remedy them. The document indicates the specific elements of the cooperation that need to be corrected, for example the way instructions are given, the organisation of working time or the scope of the contractor’s responsibility. The order is not yet a sanction, but it constitutes a formal warning.


An administrative decision on the existence of an employment relationship

If the company does not implement the changes indicated in the order, the district inspector may issue an administrative decision establishing the existence of an employment relationship. This is the most severe consequence of an inspection, because the decision takes immediate effect and entails an obligation to make tax and contribution corrections as well as organisational changes.


An individual interpretation from PIP

Companies may apply for an individual interpretation, which protects them against sanctions provided that the actual state of affairs corresponds to the one described in the application. This is a preventive tool, particularly useful during the adjustment period running until 8 July 2027.


What are the consequences of B2B cooperation being challenged?

Classifying B2B cooperation as an employment relationship is one of the most severe outcomes of a PIP inspection. Following the changes in the legislation, an inspector’s decision may take immediate effect through the imposition of immediate enforceability. This means rapid financial burdens, the need to reorganise processes and legal risks that may affect the stability of the entire engagement model.


Financial consequences: outstanding contributions, taxes and top-up payments

Moreover, reclassification may result in the need to pay public law liabilities, including:

  • ZUS contributions,
  • PIT advance payments.

And, in addition, the need to:

  • top up employee entitlements, such as holiday pay equivalents, overtime supplements or other entitlements arising from the Labour Code,
  • correct payroll documentation and ZUS filings.

In practice this often means corrections covering many months, which may place a significant burden on the organisation’s budget.


Organisational consequences: changes to the working model and team structures

Reclassification forces the cooperation model to be adjusted. The company must:

  • employ the person concerned under an employment contract or change the way the services are provided,
  • implement full employment processes: working time records, occupational health and safety rules, holidays, breaks, overtime,
  • reorganise teams, if the model used to date was based on a large number of contractors,
  • adapt tools, systems and procedures to labour law requirements.

In companies using B2B on a large scale, this may mean rebuilding the entire operating model.


Legal consequences: management board liability and the risk of disputes

An inspector’s decision may trigger further proceedings:

  • liability of management board members for infringements of employment provisions,
  • fiscal penal proceedings connected with incorrect tax settlements,
  • claims by contractors, who may pursue employee entitlements for the entire period of cooperation,
  • the need to correct HR and payroll documentation.

This is an area that simultaneously involves the legal department, HR, accounting and the management board.


Reputational consequences: loss of trust and destabilisation of cooperation

Reclassification may also affect the company’s image:

  • it weakens contractors’ trust,
  • it makes recruitment in the B2B model more difficult,
  • it affects relations with business partners,
  • it forces crisis communication within the organisation.

In industries based on flexibility and specialist services, this is felt particularly keenly.


Which companies are most exposed?

The risk of B2B cooperation being challenged is not spread evenly across all organisations. PIP focuses primarily on companies in which the model of cooperation with contractors is widely used and day-to-day practice may resemble an employment relationship. What matters is not only the number of people on B2B, but also the way work is organised, the structure of teams and the nature of the services provided.


Companies with a large number of contractors

Organisations that base a significant part of their operations on B2B cooperation are naturally more visible in risk analyses. This applies both to large project teams and to companies that have replaced employment positions with contracts over the years. The greater the scale of the cooperation, the greater the likelihood that PIP will want to verify whether the model complies with the law.


Industries with repetitive working patterns

The highest risk concerns sectors in which contractors work in a manner close to that of employees: at fixed hours, within teams, under ongoing managerial supervision. These are above all:

  • IT and software development,
  • marketing and the creative industry,
  • e-commerce and logistics,
  • shared services centres (SSC/BPO),
  • manufacturing and industry,
  • technology and design companies.

In these sectors the line between a service and employment can be especially thin.


Organisations with extensive reporting structures

Companies that require contractors to report working time, attend regular meetings, use internal tools or comply with procedures typical of employment are more exposed to inspection. PIP analyses whether the contractor actually operates as an independent entity or is integrated into the organisational structure.


Entities offering contractors employee benefits

The risk increases where contractors use benefits typical of employment, such as private medical care, sports cards, internal training or company events. Inspectors treat this as a signal that the company treats the contractor as an employee rather than as an independent service provider.


Companies with lump-sum, fixed remuneration

Fixed, recurring remuneration, independent of the results of the work or the scope of the services, is one of the elements that may suggest that self-employment is a sham. PIP pays attention to whether the contractor bears economic risk or receives remuneration in a manner typical of employment.


How to safeguard B2B cooperation? A practical plan for companies

Effectively safeguarding B2B cooperation requires a process-based approach. A correctly drafted contract is not enough, because what is crucial is that the way the services are performed genuinely reflects a business model rather than an employment one. The plan below sets out measures that genuinely reduce the risk of the cooperation being challenged by PIP.


1. Audit your contracts and operational practice

The audit should cover both documents and the day-to-day organisation of work. In practice this means analysing:

  • the content of the B2B contracts, the scopes of services and the rules on responsibility,
  • the way tasks are delegated and communication with contractors is handled,
  • schedules, reports, timesheets and project documentation,
  • the remuneration structure and settlement rules,
  • contractors’ integration with the team and internal processes.

The aim is to establish whether operational practice is consistent with the B2B model.


2. Design a cooperation model consistent with the law and with PIP’s practice

On the basis of the audit, the company should implement a model that minimises the risk of reclassification. This includes, among other things:

  • clearly defining the scope of services and the deliverables,
  • ensuring a genuine possibility of substitution,
  • avoiding fixed working hours and mandatory presence in the office,
  • emphasising the contractor’s independence within operational processes,
  • adjusting the remuneration structure so that it reflects the nature of the services rather than an employment pay scheme.


3. Introduce procedures governing B2B cooperation

Procedures are among the most important pieces of evidence during a PIP inspection. They should cover:

  • instructions for managers on communication and delegating tasks,
  • rules on onboarding contractors,
  • guidelines on reporting and settlements,
  • documentation confirming the provider’s independence (e.g. acceptance protocols, declarations).

Well-prepared procedures prevent practice from “drifting apart” from the wording of the contracts.


4. Train managers and teams

Most errors in the B2B model stem from a lack of operational awareness. Training should cover:

  • the differences between B2B and employment,
  • the rules on giving instructions,
  • the elements that may lead to reclassification,
  • managers’ responsibility for keeping practice consistent with the documentation.

This is a key element, because it is precisely the day-to-day actions of teams that PIP most often analyses.


5. Monitor compliance and update documentation

The B2B model requires ongoing oversight. Companies should:

  • regularly verify the consistency of practice with the documentation,
  • update contracts and procedures,
  • respond to changes in the legislation,
  • consult advisers on atypical cases.

Continuous monitoring makes it possible to maintain consistency between theory and practice.


6. Consider applying for an individual interpretation from PIP
An individual interpretation can confirm that a given cooperation model complies with the law. This is particularly useful in the case of:
  • large teams of contractors,
  • high-value projects,
  • atypical cooperation models,
  • industries with a heightened risk of inspection.

An interpretation protects the company provided that the actual state of affairs corresponds to the description in the application.


How will companies feel the new inspection rules?

The new B2B inspection rules force companies to change their approach to cooperation with contractors. A model that for years functioned mainly as a flexible alternative to employment now requires considerably greater operational discipline. Organisations must ensure consistency between documentation and day-to-day practice, clearly define the limits of providers’ independence and manage risk consciously. In practice this means the need for continuous process monitoring, greater responsibility on the part of managers and a readiness to respond quickly to signals of non-compliance. Companies that treat this area strategically may continue to use B2B, though no longer intuitively, but in a conscious and orderly way.


How does ALTO Advisory help companies through the changes?

ALTO Advisory supports companies in putting B2B cooperation in order from both a legal and an operational perspective. Our team of advisers helps carry out a risk audit, prepare a safe cooperation model, develop procedures for managers and put in place documentation that genuinely protects the company during an inspection. Ongoing support is also an important element, such as consultations on atypical cases, updating contracts and preparing the organisation for the new supervisory obligations. This allows companies to use B2B in a way consistent with PIP’s current practice.


Summary

The changes in the way B2B cooperation is inspected mean that companies need a more conscious and orderly approach to their relationships with contractors. PIP today assesses above all practice rather than the wording of contracts, which is why organisations must ensure consistency of processes, clear rules of cooperation and appropriate preparation of managers. The B2B model can still be safe and effective, but it requires greater operational discipline and continuous risk monitoring. Properly designed procedures, regular audits and expert support allow companies to make use of B2B flexibility without fear of the consequences of an inspection.